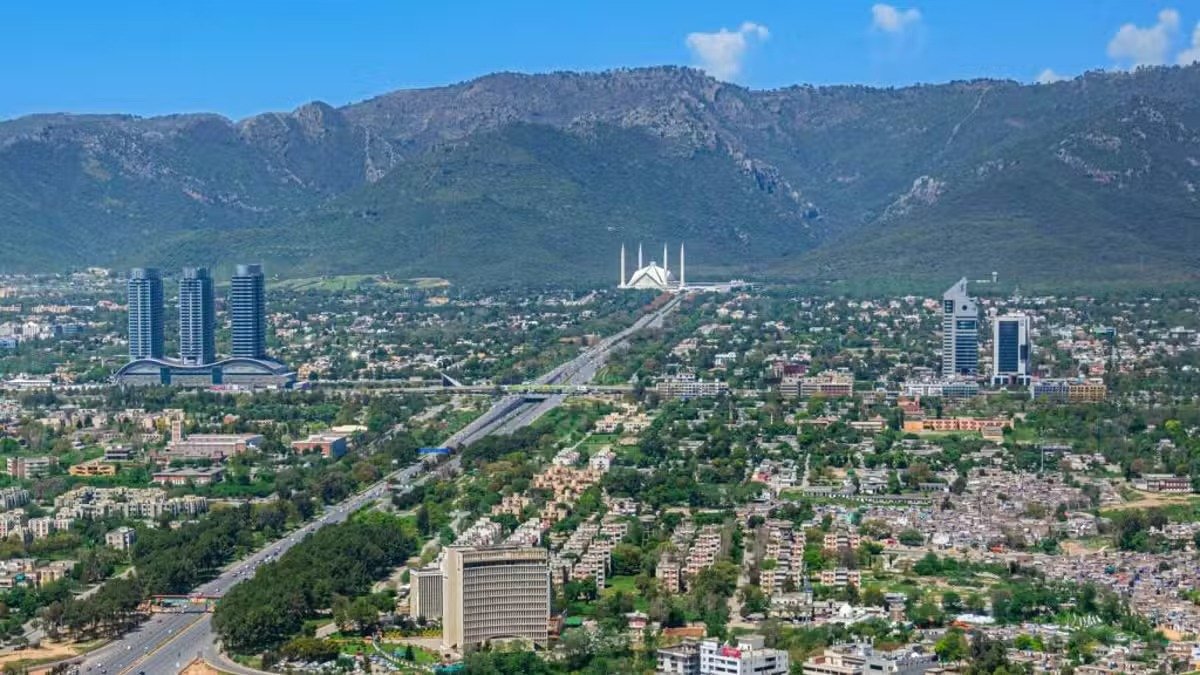
Explore Islamabad Capital Territory, the federal capital region of Pakistan known for its planned
sectors, modern infrastructure, and high-value residential and commercial real estate.
صرف انتقال کا اندراج جائیداد کی ملکیت ثابت نہیں کرتا: لاہور ہائیکورٹ
▫️ Justice Hassan Nawaz Makhdoom says mutation is primarily a fiscal entry and does not by itself create, transfer or extinguish title to property
▫️ انتقال بنیادی طور پر ریونیو ریکارڈ میں مالی نوعیت کا اندراج ہے، جو بذاتِ خود جائیداد کی ملکیت پیدا، منتقل یا ختم نہیں کرتا: جسٹس حسن نواز مخدوم
Islamabad | ReNews PakistanA court has ruled that a revenue mutation, by itself, cannot establish ownership or prove the transfer...
Islamabad | ReNews Pakistan A court has ruled that a revenue mutation, by itself, cannot establish ownership or prove the transfer of title to immovable property, rejecting a challenge based on claims that 346 kanals of land in Sargodha had been gifted decades earlier and therefore did not form part of a deceased landowner’s estate. The dispute centred on land measuring 346 kanals situated in Chak No. 29/N.B., Sargodha, which the defendants maintained had been gifted by Dost Muhammad to Ali Akbar during his lifetime. According to the defendants, the gift was reflected in Mutation No. 204 dated February 6, 1962. On this basis, they argued that the property had already passed to Ali Akbar and was no longer owned by Dost Muhammad at the time of his death. Consequently, they contended, the land could not be treated as part of the deceased’s estate for the purpose of inheritance. The defendants also disputed the inheritance claim of Sahib Khatoon, maintaining that she had been divorced by Dost Muhammad in 1921. They argued that, as a result of the alleged divorce, she was not legally entitled to inherit from him after his death. The controversy eventually reached the court after the defendants challenged findings recorded by the lower courts concerning the ownership and inheritance of the disputed property. Rejecting the challenge to the lower courts’ findings, Justice Hassan Nawaz Makhdoom held that the mere existence of a mutation entry in the revenue record was insufficient to establish that a valid gift of the property had taken place. The court observed that a mutation was essentially a fiscal entry maintained by revenue authorities primarily for revenue administration and collection purposes. Such an entry, the court said, did not by itself create, confer or extinguish title to immovable property. The judgment emphasised that where ownership was claimed on the basis of a gift, the party relying on that transaction was required to establish the underlying gift through legally admissible and credible evidence rather than relying solely on its entry in the revenue record. In the present case, the court noted that the defendants had failed to produce any witness connected with the original gift transaction. Nor had they presented independent evidence capable of establishing that Dost Muhammad had actually made the alleged gift in favour of Ali Akbar. The absence of evidence supporting the underlying transaction weakened the defendants’ reliance on Mutation No. 204, as the mutation itself could not substitute for proof of the transaction through which ownership was claimed to have been transferred. The ruling therefore upheld the principle that entries in revenue records are not, standing alone, conclusive proof of ownership and that a party asserting title on the basis of an alleged gift must independently prove the transaction on which that claim rests. The case also involved the defendants’ contention regarding Sahib Khatoon’s alleged divorce and her consequent entitlement to inheritance, making the dispute significant not only in relation to the evidentiary value of revenue records but also to the determination of succession rights in the deceased’s estate.
اسلام آباد | ری نیوز پاکستان لاہور ہائیکورٹ نے قرار دیا ہے کہ ریونیو ریکارڈ میں محض انتقال کا اندراج کسی غیر منقولہ جائیداد کی ملکیت یا اس کی منتقلی ثابت کرنے کے لیے کافی نہیں۔ عدالت نے سرگودھا میں 346 کنال اراضی سے متعلق اس دعوے کو مسترد کر دیا جس میں کہا گیا تھا کہ مذکورہ زمین کئی دہائیاں قبل ہبہ کردی گئی تھی اور اس لیے مالک کی وفات کے وقت یہ اس کے ترکے کا حصہ نہیں تھی۔
تنازع سرگودھا کے چک نمبر 29 این بی میں واقع 346 کنال اراضی سے متعلق تھا۔ مدعا علیہان کا مؤقف تھا کہ دوست محمد نے اپنی زندگی میں یہ زمین علی اکبر کو بطور ہبہ دے دی تھی۔
مدعا علیہان کے مطابق، اس ہبہ کا اندراج انتقال نمبر 204 کے ذریعے 6 فروری 1962 کو کیا گیا تھا۔ اسی بنیاد پر انہوں نے مؤقف اختیار کیا کہ زمین دوست محمد کی زندگی ہی میں علی اکبر کو منتقل ہوچکی تھی اور دوست محمد کی وفات کے وقت وہ اس کی ملکیت نہیں رہی تھی، لہٰذا اسے وراثت کی تقسیم کے لیے متوفی کے ترکے کا حصہ قرار نہیں دیا جاسکتا۔
مدعا علیہان نے صاحب خاتون کے حقِ وراثت کو بھی چیلنج کیا۔ ان کا مؤقف تھا کہ دوست محمد نے 1921 میں صاحب خاتون کو طلاق دے دی تھی، اس لیے دوست محمد کی وفات کے بعد وہ اس کی وارث بننے کی حق دار نہیں تھیں۔
جائیداد کی ملکیت اور وراثتی حقوق سے متعلق ماتحت عدالتوں کے فیصلوں کو مدعا علیہان کی جانب سے چیلنج کیے جانے کے بعد معاملہ لاہور ہائیکورٹ پہنچا۔
ماتحت عدالتوں کے فیصلوں کے خلاف اعتراضات مسترد کرتے ہوئے جسٹس حسن نواز مخدوم نے قرار دیا کہ ریونیو ریکارڈ میں محض انتقال موجود ہونے سے یہ ثابت نہیں ہوتا کہ جائیداد کا ہبہ قانونی طور پر واقع ہوچکا تھا۔
عدالت نے قرار دیا کہ انتقال بنیادی طور پر ریونیو حکام کی جانب سے مالی اور محصولات سے متعلق مقاصد کے لیے رکھا جانے والا اندراج ہے۔ ایسا اندراج بذاتِ خود کسی غیر منقولہ جائیداد میں ملکیتی حق پیدا نہیں کرتا، نہ ملکیت منتقل کرتا ہے اور نہ ہی کسی کے ملکیتی حقوق ختم کرتا ہے۔
فیصلے میں واضح کیا گیا کہ اگر کوئی فریق ہبہ کی بنیاد پر جائیداد کی ملکیت کا دعویٰ کرتا ہے تو اس پر لازم ہے کہ وہ اصل ہبہ کو قانونی طور پر قابلِ قبول اور قابلِ اعتماد شواہد کے ذریعے ثابت کرے۔ محض ریونیو ریکارڈ میں انتقال کا اندراج اس مقصد کے لیے کافی نہیں۔
عدالت نے قرار دیا کہ زیر سماعت مقدمے میں مدعا علیہان مبینہ ہبہ کے اصل لین دین سے متعلق کوئی گواہ پیش کرنے میں ناکام رہے۔ اسی طرح کوئی ایسا آزاد ثبوت بھی عدالت کے سامنے پیش نہیں کیا گیا جس سے یہ ثابت ہوسکے کہ دوست محمد نے حقیقتاً مذکورہ زمین علی اکبر کو ہبہ کی تھی۔
عدالت کے مطابق، اصل ہبہ کے حق میں شواہد کی عدم موجودگی نے انتقال نمبر 204 پر مدعا علیہان کے انحصار کو کمزور کردیا، کیونکہ انتقال کا اندراج اس بنیادی لین دین کے ثبوت کا متبادل نہیں ہوسکتا جس کے ذریعے جائیداد کی ملکیت منتقل ہونے کا دعویٰ کیا گیا ہو۔
فیصلے میں اس قانونی اصول کو برقرار رکھا گیا کہ ریونیو ریکارڈ میں موجود اندراجات بذاتِ خود ملکیت کا حتمی ثبوت نہیں ہوتے اور ہبہ کی بنیاد پر ملکیتی حق کا دعویٰ کرنے والے فریق کو اس اصل لین دین کو آزادانہ اور قابلِ اعتماد شواہد سے ثابت کرنا ضروری ہے۔
مقدمے میں صاحب خاتون کی مبینہ طلاق اور اس کے نتیجے میں ان کے حقِ وراثت کا معاملہ بھی زیر بحث آیا، جس کے باعث یہ تنازع نہ صرف ریونیو ریکارڈ اور انتقال کی قانونی حیثیت بلکہ متوفی کی جائیداد میں وراثتی حقوق کے تعین کے حوالے سے بھی اہمیت کا حامل ہے۔
Published: October 3, 2026 at 12:01 PM
FBR Cuts Sales Tax on Steel Units in Former FATA, PATA Areas
سابق فاٹا اور پاٹا میں سٹیل یونٹس کیلئے سیلز ٹیکس کی شرح کم کر دی گئی
▫️ Steel melters, composite units and re-rollers to pay sales tax at Rs 20 per electricity unit under revised tax regime
▫️ جی ٹی روڈ کے 16 کلومیٹر طویل حصے پر تقریباً 2 ہزار کنال اراضی کمرشل سرگرمیوں کیلئے مختص کیے جانے کا امکان
Islamabad | ReNews PakistanThe Federal Board of Revenue (FBR) has reduced sales tax rates for steel manufacturers operating in the...
Islamabad | ReNews Pakistan The Federal Board of Revenue (FBR) has reduced sales tax rates for steel manufacturers operating in the former Federally Administered Tribal Areas (FATA) and Provincially Administered Tribal Areas (PATA), providing tax relief to steel melters, composite units and re-rollers in the regions. Under the revised arrangement, steel melters and composite units using locally purchased remeltable steel scrap will be required to pay sales tax at the rate of Rs20 per unit of electricity consumed. Steel re-rolling units manufacturing steel bars from imported or locally procured raw materials will also be subject to sales tax at Rs 20 per electricity unit consumed. The FBR introduced the revised rates through S.R.O. 1664(I)/2026, amending the earlier S.R.O. 1245(I)/2026 and modifying the mechanism for determining sales tax liability of eligible steel units operating in the former FATA and PATA territories. The notification also provides a substantially lower sales tax rate for certain steel melters and composite units that rely predominantly on imported raw materials or remeltable steel scrap acquired directly from persons registered under the Export Facilitation Scheme (EFS). Under the revised mechanism, eligible steel melters and composite units will pay sales tax at Rs 5 per electricity unit if their consumption of imported raw material or remeltable steel scrap purchased directly from EFS-registered persons exceeds 70 percent of their aggregate raw-material consumption during the preceding 12 months. The preferential Rs 5 rate is therefore linked to the composition of raw materials used by the units, while businesses that do not meet the prescribed threshold will remain subject to the Rs 20-per-unit rate. Steel re-rollers, however, will continue to pay sales tax at Rs 20 per electricity unit consumed, irrespective of whether imported or locally sourced raw materials are used in the manufacture of steel bars. The FBR has also established a separate eligibility mechanism for newly established steel businesses and previously closed units that have resumed operations. Since such businesses may not have a 12-month operating history available for assessing their raw-material consumption, their eligibility for the concessional Rs5-per-unit sales tax rate will be determined on the basis of their quarterly imports or purchases. The arrangement is intended to provide a workable mechanism for calculating sales tax liabilities of steel manufacturers in the former tribal areas while continuing concessions available to businesses operating in these territories under the Sales Tax Act, 1990. The change could lower the tax component of production costs for qualifying steel manufacturers, particularly melters and composite units meeting the 70-percent raw-material threshold. The extent to which the relief translates into lower steel prices, however, will also depend on other production costs and market conditions. The revised tax regime forms part of the special sales tax treatment applicable to the former FATA and PATA regions, where the government has maintained concessions for eligible businesses following the administrative and constitutional changes affecting the former tribal territories.
اسلام آباد | ری نیوز پاکستان فیڈرل بورڈ آف ریونیو (ایف بی آر) نے سابق وفاق کے زیر انتظام قبائلی علاقوں (فاٹا) اور صوبائی زیر انتظام قبائلی علاقوں (پاٹا) میں کام کرنے والے سٹیل مینوفیکچررز کیلئے سیلز ٹیکس کی شرح میں کمی کر دی ہے، جس سے ان علاقوں میں قائم سٹیل میلٹرز، کمپوزٹ یونٹس اور ری رولرز کو ٹیکس ریلیف ملے گا۔
نظرثانی شدہ نظام کے تحت مقامی طور پر خریدے گئے دوبارہ پگھلائے جانے کے قابل سٹیل سکریپ استعمال کرنے والے سٹیل میلٹرز اور کمپوزٹ یونٹس سے بجلی کے استعمال پر 20 روپے فی یونٹ کے حساب سے سیلز ٹیکس وصول کیا جائے گا۔
اسی طرح درآمدی یا مقامی خام مال استعمال کرکے سٹیل بارز تیار کرنے والے سٹیل ری رولنگ یونٹس بھی استعمال شدہ بجلی پر 20 روپے فی یونٹ کے حساب سے سیلز ٹیکس ادا کریں گے۔
ایف بی آر نے ایس آر او 1664(I)/2026 کے ذریعے نظرثانی شدہ شرحیں متعارف کرائی ہیں۔ اس اقدام کے تحت سابقہ ایس آر او 1245(I)/2026 میں ترمیم کرتے ہوئے سابق فاٹا اور پاٹا میں اہل سٹیل یونٹس کی سیلز ٹیکس واجبات کے تعین کے طریقہ کار میں تبدیلی کی گئی ہے۔
نوٹیفکیشن میں بعض سٹیل میلٹرز اور کمپوزٹ یونٹس کیلئے سیلز ٹیکس کی مزید کم شرح بھی مقرر کی گئی ہے، بالخصوص ایسے یونٹس جو زیادہ تر درآمدی خام مال یا ایکسپورٹ فیسلی ٹیشن سکیم (ای ایف ایس) کے تحت رجسٹرڈ افراد سے براہ راست خریدا گیا دوبارہ پگھلائے جانے کے قابل سٹیل سکریپ استعمال کرتے ہیں۔
نظرثانی شدہ طریقہ کار کے مطابق اگر کسی اہل سٹیل میلٹر یا کمپوزٹ یونٹ کے درآمدی خام مال یا ای ایف ایس کے تحت رجسٹرڈ افراد سے براہ راست خریدے گئے ری میلٹیبل سٹیل سکریپ کا استعمال گزشتہ 12 ماہ کے دوران اس کے مجموعی خام مال کے 70 فیصد سے زیادہ ہو تو ایسے یونٹ سے بجلی کے استعمال پر صرف 5 روپے فی یونٹ کے حساب سے سیلز ٹیکس وصول کیا جائے گا۔
اس طرح 5 روپے فی یونٹ کی رعایتی شرح کا انحصار متعلقہ یونٹ کے زیر استعمال خام مال کی نوعیت اور تناسب پر ہوگا، جبکہ مقررہ 70 فیصد کی حد پوری نہ کرنے والے کاروباری اداروں پر 20 روپے فی یونٹ کی شرح برقرار رہے گی۔
تاہم سٹیل ری رولرز کیلئے بجلی کے استعمال پر سیلز ٹیکس کی شرح 20 روپے فی یونٹ ہی برقرار رہے گی، خواہ وہ سٹیل بارز کی تیاری کیلئے درآمدی خام مال استعمال کریں یا مقامی طور پر حاصل کردہ مواد۔
ایف بی آر نے نئے قائم ہونے والے سٹیل کاروباری اداروں اور پہلے بند رہنے کے بعد دوبارہ کام شروع کرنے والے یونٹس کیلئے بھی رعایتی شرح کے تعین کا الگ طریقہ کار وضع کیا ہے۔
چونکہ ایسے کاروباری اداروں کے پاس خام مال کے استعمال کا گزشتہ 12 ماہ کا ریکارڈ دستیاب نہیں ہوسکتا، اس لیے 5 روپے فی یونٹ کی رعایتی سیلز ٹیکس شرح کیلئے ان کی اہلیت کا تعین سہ ماہی بنیادوں پر کی جانے والی درآمدات یا خریداریوں کی بنیاد پر کیا جائے گا۔
نئے انتظام کا مقصد سابق قبائلی علاقوں میں سٹیل مینوفیکچررز کی سیلز ٹیکس واجبات کے تعین کیلئے قابل عمل طریقہ کار فراہم کرنا ہے، جبکہ سیلز ٹیکس ایکٹ 1990 کے تحت ان علاقوں میں کاروباری اداروں کو حاصل رعایتیں بھی جاری رکھی جائیں گی۔
ٹیکس شرح میں کمی سے اہل سٹیل مینوفیکچررز، خصوصاً 70 فیصد خام مال کی مقررہ حد پوری کرنے والے سٹیل میلٹرز اور کمپوزٹ یونٹس کی پیداواری لاگت میں شامل ٹیکس کے بوجھ میں کمی آسکتی ہے۔ تاہم اس ریلیف کے نتیجے میں سٹیل کی مارکیٹ قیمتوں میں کس حد تک کمی آئے گی، اس کا انحصار دیگر پیداواری اخراجات اور مارکیٹ کی صورتحال پر بھی ہوگا۔
نظرثانی شدہ ٹیکس نظام سابق فاٹا اور پاٹا کیلئے خصوصی سیلز ٹیکس نظام کا حصہ ہے، جس کے تحت سابق قبائلی علاقوں میں انتظامی اور آئینی تبدیلیوں کے بعد بھی اہل کاروباری اداروں کیلئے مخصوص ٹیکس مراعات برقرار رکھی گئی ہیں۔
Published: October 3, 2026 at 10:01 AM
CDA Eyes Rs 500 Billion Revenue From Major G.T. Road Commercial Project
جی ٹی روڈ پر بڑے کمرشل منصوبے سے سی ڈی اے کو 500 ارب روپے آمدن کی توقع
▫️ Around 2,000 kanals along a 16-kilometre stretch of G.T. Road could be opened for commercial development
▫️ جی ٹی روڈ کے 16 کلومیٹر طویل حصے پر تقریباً 2 ہزار کنال اراضی کمرشل سرگرمیوں کیلئے مختص کیے جانے کا امکان
Islamabad | ReNews PakistanThe Capital Development Authority (CDA) is preparing to launch a major commercial development project along G.
Islamabad | ReNews Pakistan The Capital Development Authority (CDA) is preparing to launch a major commercial development project along G.T. Road in Islamabad, with officials estimating that the initiative could generate more than Rs500 billion in revenue for the civic body. CDA Chairman Sohail Ashraf has directed the relevant departments to accelerate planning and other preparatory work for the project, which the authority expects to launch in the coming months. Rather than developing or selling the entire area simultaneously, the CDA plans to undertake the project in phases. Officials believe the phased approach will allow the authority to manage development more effectively while gradually bringing commercially viable land to the market. The project is planned on land acquired by the CDA nearly six decades ago. In 1967, the authority acquired approximately 3,550 kanals along a 16-kilometre stretch between EME College and Nicholson Monument. The acquired land comprises a 200-foot-wide strip running along both sides of G.T. Road, giving the authority a substantial corridor for planned commercial development. Following initial planning and assessment, CDA officials estimate that approximately 2,000 kanals of the total acquired land could eventually be made available for commercial use. If developed and sold as planned, officials expect the project to generate more than Rs500 billion for the authority, potentially making it one of the CDA's major revenue-generating commercial initiatives. The project, however, also requires the authority to address encroachments and other structures occupying portions of the acquired land. The CDA has intensified efforts to retrieve the remaining land and has already recovered a significant portion of the property from encroachments. Permanent structures standing on CDA land have also been identified and marked for removal. Officials said demolition and clearance operations involving permanent structures would proceed after the completion of the required legal procedures. More than 100 permanent buildings are estimated to be occupying CDA-owned land within the project area, making land recovery an important component of preparations for the proposed commercial development. Alongside the anti-encroachment drive, the authority has begun work on finalising the project's design and planning framework. Director General Spatial Planning Ijaz Ahmad Sheikh has constituted a four-member committee to complete the design of the proposed development. The committee is headed by Deputy Director General Architecture Ali Abdullah. The committee's work is expected to determine how the available land will be divided, planned and developed for commercial purposes before individual phases are brought to the market. The project could also unlock the commercial potential of a sizeable tract of CDA-owned land along one of the major road corridors connecting Islamabad and Rawalpindi with other parts of the country. With planning, land recovery and design work proceeding simultaneously, the CDA is seeking to move the project towards implementation and launch its initial phases in the coming months.
اسلام آباد | ری نیوز پاکستان کیپیٹل ڈویلپمنٹ اتھارٹی (سی ڈی اے) اسلام آباد میں جی ٹی روڈ کے ساتھ ایک بڑے کمرشل منصوبے کے آغاز کی تیاری کر رہی ہے، جس سے ادارے کو 500 ارب روپے سے زائد آمدن حاصل ہونے کی توقع ہے۔
چیئرمین سی ڈی اے سہیل اشرف نے متعلقہ شعبوں کو منصوبے کی منصوبہ بندی اور دیگر ابتدائی امور پر کام تیز کرنے کی ہدایت کی ہے۔ حکام کے مطابق منصوبہ آئندہ چند ماہ کے دوران متعارف کرائے جانے کا امکان ہے۔
سی ڈی اے پورے علاقے کو بیک وقت ترقی دینے یا فروخت کرنے کے بجائے منصوبے کو مرحلہ وار مکمل کرنے کا ارادہ رکھتا ہے۔ حکام کا کہنا ہے کہ اس حکمت عملی سے ترقیاتی کام کو زیادہ مؤثر انداز میں آگے بڑھانے کے ساتھ کمرشل اراضی کو مرحلہ وار مارکیٹ میں پیش کرنا ممکن ہوگا۔
مجوزہ منصوبہ اس اراضی پر تیار کیا جائے گا جو سی ڈی اے نے تقریباً چھ دہائیاں قبل حاصل کی تھی۔ اتھارٹی نے 1967 میں ای ایم ای کالج سے نکلسن مانیومنٹ تک جی ٹی روڈ کے تقریباً 16 کلومیٹر طویل حصے کے ساتھ 3 ہزار 550 کنال اراضی حاصل کی تھی۔
یہ اراضی جی ٹی روڈ کے دونوں اطراف 200 فٹ چوڑی پٹی پر مشتمل ہے، جس کے باعث سی ڈی اے کے پاس منصوبہ بند کمرشل سرگرمیوں کے لیے ایک وسیع راہداری دستیاب ہے۔
ابتدائی منصوبہ بندی اور جائزے کے بعد سی ڈی اے حکام کا اندازہ ہے کہ مجموعی اراضی میں سے تقریباً 2 ہزار کنال زمین کمرشل مقاصد کے لیے دستیاب ہوسکتی ہے۔
حکام کے مطابق منصوبے کو طے شدہ حکمت عملی کے تحت ترقی دے کر فروخت کیا گیا تو اس سے سی ڈی اے کو 500 ارب روپے سے زائد آمدن حاصل ہوسکتی ہے، جس کے باعث یہ منصوبہ اتھارٹی کے بڑے آمدن پیدا کرنے والے کمرشل منصوبوں میں شامل ہوسکتا ہے۔
تاہم منصوبے پر عملی پیش رفت کے لیے سی ڈی اے کو اراضی پر قائم تجاوزات اور دیگر تعمیرات کا مسئلہ بھی حل کرنا ہوگا۔
سی ڈی اے نے باقی ماندہ اراضی کو تجاوزات سے واگزار کرانے کے لیے کارروائیاں تیز کردی ہیں اور حکام کے مطابق زمین کا ایک بڑا حصہ پہلے ہی واگزار کرایا جاچکا ہے۔ سی ڈی اے کی اراضی پر قائم مستقل تعمیرات کی نشاندہی کرکے انہیں ہٹانے کے لیے مارکنگ بھی کردی گئی ہے۔
حکام کا کہنا ہے کہ مستقل تعمیرات کے خلاف انہدام اور کلیئرنس آپریشن ضروری قانونی کارروائی مکمل ہونے کے بعد شروع کیا جائے گا۔
تخمینے کے مطابق منصوبے کے علاقے میں سی ڈی اے کی ملکیتی اراضی پر 100 سے زائد مستقل عمارتیں قائم ہیں، جس کے باعث زمین واگزار کرانا منصوبے کی تیاری کے اہم مراحل میں شامل ہے۔
تجاوزات کے خلاف کارروائی کے ساتھ سی ڈی اے نے منصوبے کے ڈیزائن اور پلاننگ فریم ورک کو حتمی شکل دینے کا عمل بھی شروع کردیا ہے۔
ڈائریکٹر جنرل اسپیشل پلاننگ اعجاز احمد شیخ نے مجوزہ منصوبے کا ڈیزائن مکمل کرنے کے لیے چار رکنی کمیٹی تشکیل دی ہے، جس کی سربراہی ڈپٹی ڈائریکٹر جنرل آرکیٹیکچر علی عبداللہ کر رہے ہیں۔
کمیٹی دستیاب اراضی کی تقسیم، منصوبہ بندی اور کمرشل استعمال کے طریقہ کار کو حتمی شکل دے گی، جس کے بعد منصوبے کے مختلف مراحل کو مارکیٹ میں پیش کیا جاسکے گا۔
یہ منصوبہ سی ڈی اے کی ملکیتی وسیع اراضی کی کمرشل صلاحیت کو بروئے کار لانے میں بھی اہم کردار ادا کرسکتا ہے۔ یہ زمین ایک ایسے اہم شاہراہ پر واقع ہے جو اسلام آباد اور راولپنڈی کو ملک کے دیگر حصوں سے ملاتی ہے۔
سی ڈی اے منصوبہ بندی، اراضی واگزار کرانے اور ڈیزائن کی تیاری پر بیک وقت کام کر رہا ہے تاکہ منصوبے کو عملی مرحلے میں داخل کیا جاسکے اور آئندہ چند ماہ کے دوران اس کے ابتدائی مراحل کا آغاز کیا جاسکے۔