
Published: September 12, 2026 - 10:01 AM
Pakistan’s Housing Finance Crisis Deepens as Most Approved Loans Remain Undisbursed
پاکستان میں ہاؤسنگ فنانس کو بڑا چیلنج درپیش، بڑی تعداد میں منظور شدہ قرضوں کا اجراء تاحال نہ ہوسکا
▫️Banks approve Rs 313.42 billion in housing loans, but only Rs 45.43 billion has been disbursed to 8,739 borrowers
Islamabad | ReNews PakistanPakistan’s housing finance sector continues to face a major gap between loan approvals and actual disbursements, raising questions over whether the government’s Apna Ghar Scheme can significantly expand mortgag...
Islamabad | ReNews Pakistan
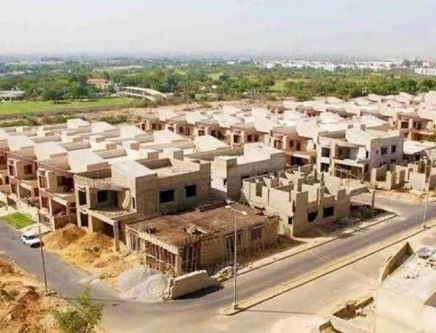
Pakistan’s housing finance sector continues to face a major gap between loan approvals and actual disbursements, raising questions over whether the government’s Apna Ghar Scheme can significantly expand mortgage lending without deeper reforms to the banking and legal systems.
A property survey ordered by the prime minister to identify plots that could qualify as mortgage collateral under the Apna Ghar Scheme is expected to expand the pool of properties eligible for housing finance. However, the measure addresses only one part of a much broader problem confronting Pakistan’s mortgage market.
According to the latest figures, banks have received 147,504 housing-loan applications, of which 53,127 applications are worth Rs 313.42 billion have been approved. However, only Rs 45.43 billion has been disbursed to 8,739 borrowers.
This means that just around 16 percent of approved borrowers have actually received financing, while the amount disbursed represents only about 14 percent of the total approved loan value.
The significant difference between approved financing and actual disbursement has emerged as a key challenge for the government’s housing finance programme. While expanding the number of properties that can be used as collateral may increase eligibility, it is unlikely by itself to convince commercial banks to take on greater credit risk.
Banks, particularly private-sector lenders, remain cautious about mortgage financing because recovering money from defaulting borrowers can involve lengthy and complicated legal procedures. Weak enforcement mechanisms have consequently remained one of the major structural barriers to the expansion of mortgage lending in Pakistan.
Housing finance currently accounts for less than 1 percent of total bank lending in Pakistan, significantly below levels seen in comparable economies where more efficient mortgage recovery mechanisms allow banks to allocate a larger share of their portfolios to housing loans.
Experts and policymakers have therefore increasingly stressed the need for reforms to mortgage enforcement, foreclosure and loan recovery procedures. A faster and more predictable recovery system, while ensuring adequate protection for borrowers against arbitrary treatment, could make property backed lending more commercially viable for banks.
The government has also been urged to publish regular data showing the number of rejected mortgage applications as well as approved loans that remain undisbursed. Such information could help identify whether the main obstacles are related to property documentation, borrower eligibility, bank risk assessments, legal requirements or other factors.
The inclusion of major private developers in the Apna Ghar programme could help increase access to housing finance, but it cannot replace broader reforms required to make mortgage lending sustainable across the banking sector.
Relying primarily on public sector banks could produce a temporary increase in disbursements, but limited participation by private banks would prevent the development of a competitive mortgage market capable of sustaining long term housing finance.
The ultimate test of the Apna Ghar Scheme, therefore, will not simply be the number of applications approved or properties identified as eligible collateral. Its success will depend on whether it can generate lasting mortgage credit across Pakistan’s banking industry.
For the housing finance market to mature, lending against property must eventually become routine commercial banking business rather than an activity driven primarily by government pressure or special schemes.
اسلام آباد | ری نیوز پاکستان
پاکستان کے ہاؤسنگ فنانس سیکٹر میں قرضوں کی منظوری اور اصل رقم کی فراہمی کے درمیان نمایاں فرق سامنے آ گیا، جس سے یہ سوال اٹھ رہا ہے کہ حکومتی اپنا گھر سکیم بینکاری اور قانونی نظام میں بنیادی اصلاحات کے بغیر مارگیج فنانسنگ کو کس حد تک فروغ دے سکے گی۔
وزیراعظم کی ہدایت پر اپنا گھر سکیم کے تحت مارگیج کے لیے اہل پلاٹس کی نشاندہی کرنے کے لیے کرایا جانے والا پراپرٹی سروے ہاؤسنگ فنانس کے لیے قابلِ قبول جائیدادوں کا دائرہ بڑھا سکتا ہے، تاہم یہ اقدام پاکستان کے مارگیج مارکیٹ کو درپیش وسیع تر مسائل کے صرف ایک حصے کو حل کرتا ہے۔
تازہ اعداد و شمار کے مطابق بینکوں کو ہاؤسنگ قرضوں کے لیے 147,504 درخواستیں موصول ہوئیں، جن میں سے 53,127 درخواستیں 313.42 ارب روپے مالیت کے قرضوں کے لیے منظور کی گئیں۔ تاہم اب تک صرف 8,739 قرض لینے والوں کو 45.43 ارب روپے جاری کیے گئے ہیں۔
اس کا مطلب ہے کہ منظور شدہ درخواست گزاروں میں سے صرف تقریباً 16 فیصد کو عملی طور پر قرض کی رقم مل سکی، جبکہ جاری کی جانے والی رقم مجموعی منظور شدہ مالیت کا صرف تقریباً 14 فیصد ہے۔
منظور شدہ قرضوں اور اصل ڈسبرسمنٹ کے درمیان یہ بڑا فرق حکومت کے ہاؤسنگ فنانس پروگرام کے لیے ایک اہم چیلنج بن کر سامنے آیا ہے۔ اگرچہ مارگیج کے لیے قابلِ قبول جائیدادوں کی تعداد بڑھانے سے زیادہ افراد اہل ہوسکتے ہیں، تاہم صرف یہ اقدام کمرشل بینکوں کو زیادہ کریڈٹ رسک لینے پر آمادہ کرنے کے لیے کافی نہیں ہوگا۔
خصوصاً نجی شعبے کے بینک مارگیج فنانسنگ کے حوالے سے محتاط ہیں، کیونکہ قرض نادہندہ ہونے کی صورت میں رقم کی وصولی ایک طویل اور پیچیدہ قانونی عمل بن سکتی ہے۔ قرضوں کی وصولی اور مارگیج کے نفاذ کے کمزور نظام کو پاکستان میں ہاؤسنگ فنانس کے فروغ میں ایک بڑی سٹرکچرل رکاوٹ سمجھا جاتا ہے۔
پاکستان میں ہاؤسنگ فنانس اس وقت بینکوں کی مجموعی فنانسنگ کا ایک فیصد سے بھی کم ہے، جو دیگر ہم پلہ معیشتوں کے مقابلے میں انتہائی کم ہے۔ ان ممالک میں مارگیج قرضوں کی وصولی کا نسبتاً مؤثر نظام بینکوں کو اپنے قرضہ پورٹ فولیو کا زیادہ حصہ ہاؤسنگ فنانس کے لیے مختص کرنے میں مدد دیتا ہے۔
ماہرین اور پالیسی سازوں کی جانب سے مارگیج انفورسمنٹ، فورکلوژر اور قرضوں کی وصولی کے طریقہ کار میں اصلاحات پر زور دیا جا رہا ہے۔ ان کے مطابق قرضوں کی وصولی کا تیز رفتار اور قابلِ پیش گوئی نظام، قرض لینے والوں کو غیر منصفانہ سلوک سے تحفظ فراہم کرنے کے ساتھ ساتھ، بینکوں کے لیے جائیداد کے عوض قرض دینا زیادہ قابلِ عمل بنا سکتا ہے۔
حکومت سے یہ مطالبہ بھی کیا گیا ہے کہ وہ مسترد ہونے والی مارگیج درخواستوں اور منظور شدہ لیکن تاحال جاری نہ کیے جانے والے قرضوں کے حوالے سے باقاعدہ اعداد و شمار جاری کرے۔ اس سے یہ جاننے میں مدد مل سکتی ہے کہ رکاوٹیں جائیداد کی دستاویزات، درخواست گزار کی اہلیت، بینک کے رسک اسیسمنٹ، قانونی تقاضوں یا دیگر عوامل میں سے کس شعبے میں موجود ہیں۔
اپنا گھر پروگرام میں بڑے نجی ڈویلپرز کی شمولیت ہاؤسنگ فنانس تک رسائی بڑھانے میں مددگار ہوسکتی ہے، تاہم اس سے پورے بینکاری نظام میں مارگیج فنانسنگ کو پائیدار بنانے کے لیے درکار بنیادی اصلاحات کا متبادل فراہم نہیں ہوتا۔
اگر پروگرام کے لیے بنیادی طور پر سرکاری بینکوں پر انحصار کیا گیا تو قرضوں کی فراہمی میں عارضی اضافہ ممکن ہے، لیکن نجی بینکوں کی محدود شمولیت ایک ایسی مسابقتی مارگیج مارکیٹ کے قیام میں رکاوٹ بنے گی جو طویل مدت تک خود اپنے بل بوتے پر قائم رہ سکے۔
چنانچہ اپنا گھر سکیم کی اصل کامیابی کا پیمانہ صرف منظور شدہ درخواستوں یا مارگیج کے لیے اہل قرار دیے گئے پلاٹس کی تعداد نہیں ہوگا، بلکہ یہ ہوگا کہ پروگرام پاکستان کے پورے بینکاری نظام میں پائیدار ہاؤسنگ فنانس کو کس حد تک فروغ دیتا ہے۔
پاکستان میں ہاؤسنگ فنانس مارکیٹ کو پختہ بنانے کے لیے جائیداد کے عوض بینک قرض دینا معمول کی کمرشل بینکاری سرگرمی بنانا ہوگا، نہ کہ ایسا عمل جو صرف حکومتی دباؤ یا خصوصی سکیموں کے تحت آگے بڑھے۔