تاریخ اشاعت: August 22, 2026 - 9:14 AM
SBP Extends Housing Finance Tenor to 30 Years, Raises Loan to Value Limit to 90 Percent
سٹیٹ بینک نے ہاؤسنگ فنانس کی مدت 30 سال تک بڑھا دی، جائیداد کی 90 فیصد مالیت تک قرض کی اجازت
▫️نظرثانی شدہ رولز کے تحت قرض لینے والے جائیداد کی قیمت کا 90 فیصد تک فنانس حاصل کر سکیں گے، جبکہ ماہانہ قرض ادائیگیاں قابل استعمال آمدن کے 65 فیصد تک ہو سکیں گی
Karachi | ReNews PakistanThe State Bank of Pakistan has introduced major changes to its prudential regulations for housing finance, extending the maximum repayment period to 30 years and allowing banks and development finance institution...
Karachi | ReNews Pakistan
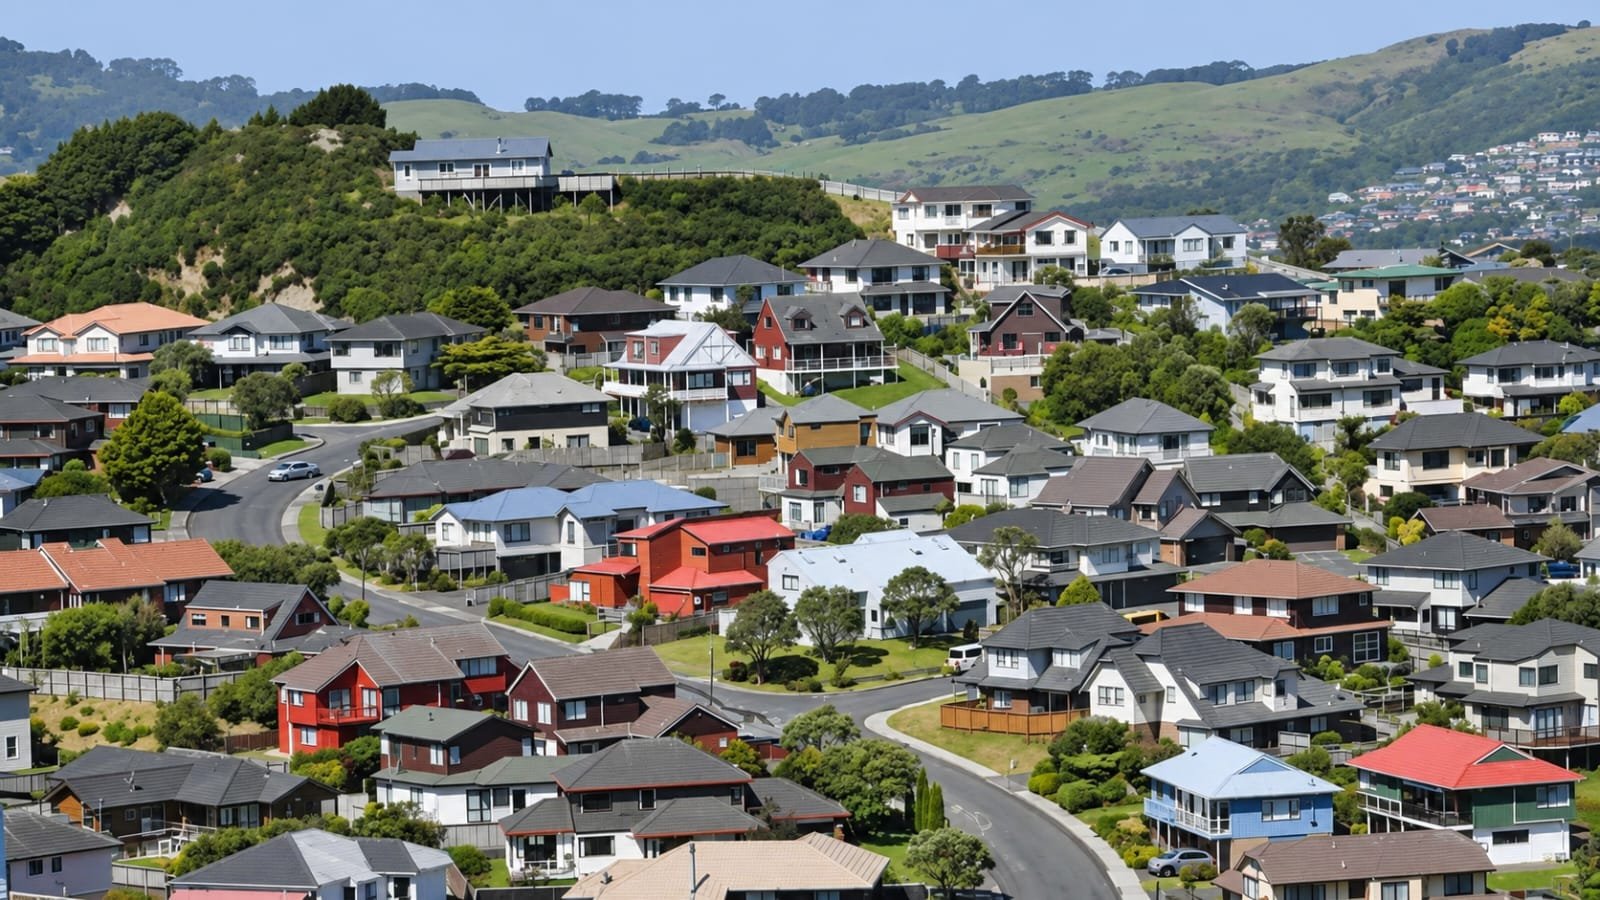
The State Bank of Pakistan has introduced major changes to its prudential regulations for housing finance, extending the maximum repayment period to 30 years and allowing banks and development finance institutions to finance up to 90 percent of the value of a residential property.
Under the revised regulations, the maximum tenor for housing finance has been increased from 20 years to 30 years, a move that could make monthly repayments more manageable for borrowers by spreading the cost of a housing loan over a longer period.
The change addresses one of the long standing constraints in Pakistan's housing finance market, where banks have traditionally been reluctant to offer longer term mortgages because much of their deposit base carries significantly shorter maturities.
According to the amended regulations, the maximum Loan to Value ratio for housing finance has been fixed at 90:10. This means eligible borrowers may obtain financing covering up to 90 percent of the value of a house or apartment, while contributing the remaining 10 percent from their own resources.
The revised framework also changes the parameters governing borrowers' repayment capacity.
Under Regulation HF 6, which deals with the Debt Burden Ratio, the combined monthly repayments of a prospective borrower, including the proposed housing finance facility and all other outstanding consumer finance obligations, must not exceed 65 percent of the borrower's net disposable income.
The provision is intended to allow banks greater flexibility in assessing housing finance applications while maintaining a formal ceiling on the amount of household income committed to debt repayments.
The SBP has also sought to widen access to mortgage finance for individuals whose earnings may not be fully documented through conventional salary slips or formal financial statements.
Banks and DFIs have been directed to use informal income estimation models, also known as proxy models, circulated by the Pakistan Banks' Association to assess the income and repayment capacity of prospective housing finance customers.
The measure could be particularly significant for self employed individuals, small business owners and people working in the informal economy who have historically faced difficulties in meeting banks' conventional income documentation requirements.
The revised regulations also clearly define the purposes for which housing finance may be provided.
Banks and DFIs may extend financing for the purchase of a house or apartment, construction of a house on a plot already owned by the borrower, or the purchase of a plot together with construction of a house on it.
Housing finance may also be used for the extension or expansion of an existing house, renovation of a residential unit and the installation of renewable energy solutions in homes.
The inclusion of renewable energy installations broadens the scope of housing finance beyond conventional property acquisition and construction, potentially allowing homeowners to finance solar and other approved energy solutions as part of their residential borrowing.
In another significant consumer facilitation measure, Regulation HF 2 requires banks and DFIs to adopt standardised and simplified housing loan application forms.
Financial institutions must also clearly specify all documents required for processing a housing finance application in both physical and digital formats.
The information and documentation requirements must be made available in both Urdu and English, making the application process easier to understand for a wider range of prospective borrowers.
The latest reforms represent an effort by the central bank to improve accessibility, affordability and transparency in Pakistan's relatively underdeveloped mortgage market.
By extending loan tenors, increasing the permissible financing share, recognising informal income and simplifying application requirements, the revised framework could expand the pool of households eligible for formal housing finance.
However, the effectiveness of the reforms will also depend on how aggressively commercial banks respond, particularly given the continuing challenge of funding long term housing loans through a banking system largely dependent on shorter term deposits.
The State Bank of Pakistan has introduced major changes to its prudential regulations for housing finance, extending the maximum repayment period to 30 years and allowing banks and development finance institutions to finance up to 90 percent of the value of a residential property.
Under the revised regulations, the maximum tenor for housing finance has been increased from 20 years to 30 years, a move that could make monthly repayments more manageable for borrowers by spreading the cost of a housing loan over a longer period.
The change addresses one of the long standing constraints in Pakistan's housing finance market, where banks have traditionally been reluctant to offer longer term mortgages because much of their deposit base carries significantly shorter maturities.
According to the amended regulations, the maximum Loan to Value ratio for housing finance has been fixed at 90:10. This means eligible borrowers may obtain financing covering up to 90 percent of the value of a house or apartment, while contributing the remaining 10 percent from their own resources.
The revised framework also changes the parameters governing borrowers' repayment capacity.
Under Regulation HF 6, which deals with the Debt Burden Ratio, the combined monthly repayments of a prospective borrower, including the proposed housing finance facility and all other outstanding consumer finance obligations, must not exceed 65 percent of the borrower's net disposable income.
The provision is intended to allow banks greater flexibility in assessing housing finance applications while maintaining a formal ceiling on the amount of household income committed to debt repayments.
The SBP has also sought to widen access to mortgage finance for individuals whose earnings may not be fully documented through conventional salary slips or formal financial statements.
Banks and DFIs have been directed to use informal income estimation models, also known as proxy models, circulated by the Pakistan Banks' Association to assess the income and repayment capacity of prospective housing finance customers.
The measure could be particularly significant for self employed individuals, small business owners and people working in the informal economy who have historically faced difficulties in meeting banks' conventional income documentation requirements.
The revised regulations also clearly define the purposes for which housing finance may be provided.
Banks and DFIs may extend financing for the purchase of a house or apartment, construction of a house on a plot already owned by the borrower, or the purchase of a plot together with construction of a house on it.
Housing finance may also be used for the extension or expansion of an existing house, renovation of a residential unit and the installation of renewable energy solutions in homes.
The inclusion of renewable energy installations broadens the scope of housing finance beyond conventional property acquisition and construction, potentially allowing homeowners to finance solar and other approved energy solutions as part of their residential borrowing.
In another significant consumer facilitation measure, Regulation HF 2 requires banks and DFIs to adopt standardised and simplified housing loan application forms.
Financial institutions must also clearly specify all documents required for processing a housing finance application in both physical and digital formats.
The information and documentation requirements must be made available in both Urdu and English, making the application process easier to understand for a wider range of prospective borrowers.
The latest reforms represent an effort by the central bank to improve accessibility, affordability and transparency in Pakistan's relatively underdeveloped mortgage market.
By extending loan tenors, increasing the permissible financing share, recognising informal income and simplifying application requirements, the revised framework could expand the pool of households eligible for formal housing finance.
However, the effectiveness of the reforms will also depend on how aggressively commercial banks respond, particularly given the continuing challenge of funding long term housing loans through a banking system largely dependent on shorter term deposits.
کراچی | ری نیوز پاکستان
سٹیٹ بینک آف پاکستان نے ہاؤسنگ فنانس سے متعلق محتاط مالیاتی رولز میں اہم تبدیلیاں متعارف کرا دی ہیں، جن کے تحت ہاؤسنگ قرض کی زیادہ سے زیادہ مدت 20 سال سے بڑھا کر 30 سال کر دی گئی ہے، جبکہ بینکوں اور ترقیاتی مالیاتی اداروں کو رہائشی جائیداد کی مالیت کے 90 فیصد تک فنانسنگ کی اجازت دے دی گئی ہے۔
نظرثانی شدہ رولز کے مطابق ہاؤسنگ فنانس کی زیادہ سے زیادہ مدت اب 30 سال ہوگی۔ اس تبدیلی سے قرض لینے والوں کیلئے ماہانہ اقساط نسبتاً کم ہو سکتی ہیں کیونکہ قرض کی واپسی زیادہ طویل مدت میں تقسیم ہو جائے گی۔
پاکستان میں ہاؤسنگ فنانس کے شعبے کو طویل عرصے سے طویل مدتی وسائل کی کمی کا سامنا رہا ہے۔ بینکوں کا مؤقف رہا ہے کہ ان کے بیشتر ڈپازٹس نسبتاً مختصر مدت کے ہوتے ہیں، اس لیے طویل مدت کیلئے ہاؤسنگ قرض فراہم کرنا مشکل رہتا ہے۔
سٹیٹ بینک کے ترمیم شدہ رولز کے تحت ہاؤسنگ فنانس کیلئے قرض اور جائیداد کی مالیت کا زیادہ سے زیادہ تناسب 90:10 مقرر کیا گیا ہے۔ اس کا مطلب یہ ہے کہ اہل قرض لینے والا مکان یا اپارٹمنٹ کی مالیت کا 90 فیصد تک قرض حاصل کر سکے گا، جبکہ باقی 10 فیصد رقم اسے اپنے وسائل سے ادا کرنا ہوگی۔
نظرثانی شدہ ضوابط میں قرض لینے والوں کی ادائیگی کی صلاحیت جانچنے کے طریقہ کار میں بھی تبدیلی کی گئی ہے۔
ریگولیشن HF 6 کے تحت زیر غور ہاؤسنگ فنانس سمیت قرض لینے والے کی تمام صارف قرضوں کی مجموعی ماہانہ اقساط اس کی قابل استعمال خالص آمدن کے 65 فیصد سے زیادہ نہیں ہو سکیں گی۔
اس شق کا مقصد بینکوں کو ہاؤسنگ قرض کی درخواستوں کا جائزہ لینے میں زیادہ گنجائش دینا ہے، تاہم ساتھ ہی یہ حد بھی مقرر کی گئی ہے کہ قرض کی ادائیگی پر گھرانے کی آمدن کا کتنا حصہ خرچ کیا جا سکتا ہے۔
سٹیٹ بینک نے ایسے افراد کیلئے بھی ہاؤسنگ فنانس تک رسائی بہتر بنانے کی کوشش کی ہے جن کی آمدن روایتی سیلری سلپ یا مکمل مالی دستاویزات کے ذریعے ثابت نہیں ہو پاتی۔
بینکوں اور ترقیاتی مالیاتی اداروں کو ہدایت دی گئی ہے کہ وہ پاکستان بینکس ایسوسی ایشن کے جاری کردہ غیر رسمی آمدن کے پراکسی ماڈلز، استعمال کرتے ہوئے درخواست گزار کی آمدن اور قرض واپس کرنے کی صلاحیت کا جائزہ لے سکیں گے۔
یہ سہولت خود روزگار افراد، چھوٹے کاروباری مالکان اور غیر رسمی شعبے میں کام کرنے والے ان افراد کیلئے خاص طور پر اہم ثابت ہو سکتی ہے جو ماضی میں مکمل آمدنی دستاویزات نہ ہونے کے باعث بینک قرض حاصل کرنے میں مشکلات کا سامنا کرتے رہے ہیں۔
نظرثانی شدہ رولز میں ان مقاصد کی بھی واضح نشاندہی کی گئی ہے جن کیلئے ہاؤسنگ فنانس حاصل کیا جا سکے گا۔
بینک اور ترقیاتی مالیاتی ادارے مکان یا اپارٹمنٹ کی خریداری، پہلے سے ملکیتی پلاٹ پر مکان کی تعمیر، پلاٹ کی خریداری اور اس پر مکان کی تعمیر کیلئے قرض فراہم کر سکیں گے۔
اس کے علاوہ موجودہ مکان کی توسیع، رہائشی یونٹ کی مرمت یا تزئین و آرائش اور گھروں میں قابل تجدید توانائی کے نظام نصب کرنے کیلئے بھی ہاؤسنگ فنانس فراہم کیا جا سکے گا۔
قابل تجدید توانائی کے نظام کو ہاؤسنگ فنانس کے دائرہ کار میں شامل کرنے سے رہائشی قرض صرف مکان خریدنے یا تعمیر کرنے تک محدود نہیں رہے گا بلکہ گھر مالکان سولر اور دیگر منظور شدہ توانائی نظام کیلئے بھی فنانسنگ حاصل کر سکیں گے۔
صارفین کیلئے ایک اور اہم سہولت کے طور پر ریگولیشن HF 2 کے تحت بینکوں اور ترقیاتی مالیاتی اداروں کو ہدایت کی گئی ہے کہ وہ ہاؤسنگ فنانس کیلئے معیاری اور آسان درخواست فارم متعارف کرائیں۔
مالیاتی اداروں کیلئے یہ بھی لازم ہوگا کہ قرض کی درخواست پر کارروائی کیلئے درکار تمام دستاویزات کی فہرست واضح طور پر فراہم کریں، خواہ درخواست کاغذی صورت میں دی جائے یا ڈیجیٹل ذریعے سے۔
تمام معلومات اور دستاویزی تقاضے اردو اور انگریزی دونوں زبانوں میں فراہم کرنا ہوں گے تاکہ زیادہ سے زیادہ افراد قرض کے طریقہ کار کو آسانی سے سمجھ سکیں۔
سٹیٹ بینک کی یہ اصلاحات پاکستان کی نسبتاً محدود ہاؤسنگ فنانس مارکیٹ میں قرض تک رسائی، استطاعت اور شفافیت بڑھانے کی کوشش کا حصہ ہیں۔
قرض کی مدت بڑھانے، جائیداد کی زیادہ مالیت تک فنانسنگ کی اجازت دینے، غیر رسمی آمدن کو تسلیم کرنے اور درخواست کے طریقہ کار کو آسان بنانے سے زیادہ گھرانے باضابطہ ہاؤسنگ فنانس کے دائرے میں آ سکتے ہیں۔
سٹیٹ بینک آف پاکستان نے ہاؤسنگ فنانس سے متعلق محتاط مالیاتی رولز میں اہم تبدیلیاں متعارف کرا دی ہیں، جن کے تحت ہاؤسنگ قرض کی زیادہ سے زیادہ مدت 20 سال سے بڑھا کر 30 سال کر دی گئی ہے، جبکہ بینکوں اور ترقیاتی مالیاتی اداروں کو رہائشی جائیداد کی مالیت کے 90 فیصد تک فنانسنگ کی اجازت دے دی گئی ہے۔
نظرثانی شدہ رولز کے مطابق ہاؤسنگ فنانس کی زیادہ سے زیادہ مدت اب 30 سال ہوگی۔ اس تبدیلی سے قرض لینے والوں کیلئے ماہانہ اقساط نسبتاً کم ہو سکتی ہیں کیونکہ قرض کی واپسی زیادہ طویل مدت میں تقسیم ہو جائے گی۔
پاکستان میں ہاؤسنگ فنانس کے شعبے کو طویل عرصے سے طویل مدتی وسائل کی کمی کا سامنا رہا ہے۔ بینکوں کا مؤقف رہا ہے کہ ان کے بیشتر ڈپازٹس نسبتاً مختصر مدت کے ہوتے ہیں، اس لیے طویل مدت کیلئے ہاؤسنگ قرض فراہم کرنا مشکل رہتا ہے۔
سٹیٹ بینک کے ترمیم شدہ رولز کے تحت ہاؤسنگ فنانس کیلئے قرض اور جائیداد کی مالیت کا زیادہ سے زیادہ تناسب 90:10 مقرر کیا گیا ہے۔ اس کا مطلب یہ ہے کہ اہل قرض لینے والا مکان یا اپارٹمنٹ کی مالیت کا 90 فیصد تک قرض حاصل کر سکے گا، جبکہ باقی 10 فیصد رقم اسے اپنے وسائل سے ادا کرنا ہوگی۔
نظرثانی شدہ ضوابط میں قرض لینے والوں کی ادائیگی کی صلاحیت جانچنے کے طریقہ کار میں بھی تبدیلی کی گئی ہے۔
ریگولیشن HF 6 کے تحت زیر غور ہاؤسنگ فنانس سمیت قرض لینے والے کی تمام صارف قرضوں کی مجموعی ماہانہ اقساط اس کی قابل استعمال خالص آمدن کے 65 فیصد سے زیادہ نہیں ہو سکیں گی۔
اس شق کا مقصد بینکوں کو ہاؤسنگ قرض کی درخواستوں کا جائزہ لینے میں زیادہ گنجائش دینا ہے، تاہم ساتھ ہی یہ حد بھی مقرر کی گئی ہے کہ قرض کی ادائیگی پر گھرانے کی آمدن کا کتنا حصہ خرچ کیا جا سکتا ہے۔
سٹیٹ بینک نے ایسے افراد کیلئے بھی ہاؤسنگ فنانس تک رسائی بہتر بنانے کی کوشش کی ہے جن کی آمدن روایتی سیلری سلپ یا مکمل مالی دستاویزات کے ذریعے ثابت نہیں ہو پاتی۔
بینکوں اور ترقیاتی مالیاتی اداروں کو ہدایت دی گئی ہے کہ وہ پاکستان بینکس ایسوسی ایشن کے جاری کردہ غیر رسمی آمدن کے پراکسی ماڈلز، استعمال کرتے ہوئے درخواست گزار کی آمدن اور قرض واپس کرنے کی صلاحیت کا جائزہ لے سکیں گے۔
یہ سہولت خود روزگار افراد، چھوٹے کاروباری مالکان اور غیر رسمی شعبے میں کام کرنے والے ان افراد کیلئے خاص طور پر اہم ثابت ہو سکتی ہے جو ماضی میں مکمل آمدنی دستاویزات نہ ہونے کے باعث بینک قرض حاصل کرنے میں مشکلات کا سامنا کرتے رہے ہیں۔
نظرثانی شدہ رولز میں ان مقاصد کی بھی واضح نشاندہی کی گئی ہے جن کیلئے ہاؤسنگ فنانس حاصل کیا جا سکے گا۔
بینک اور ترقیاتی مالیاتی ادارے مکان یا اپارٹمنٹ کی خریداری، پہلے سے ملکیتی پلاٹ پر مکان کی تعمیر، پلاٹ کی خریداری اور اس پر مکان کی تعمیر کیلئے قرض فراہم کر سکیں گے۔
اس کے علاوہ موجودہ مکان کی توسیع، رہائشی یونٹ کی مرمت یا تزئین و آرائش اور گھروں میں قابل تجدید توانائی کے نظام نصب کرنے کیلئے بھی ہاؤسنگ فنانس فراہم کیا جا سکے گا۔
قابل تجدید توانائی کے نظام کو ہاؤسنگ فنانس کے دائرہ کار میں شامل کرنے سے رہائشی قرض صرف مکان خریدنے یا تعمیر کرنے تک محدود نہیں رہے گا بلکہ گھر مالکان سولر اور دیگر منظور شدہ توانائی نظام کیلئے بھی فنانسنگ حاصل کر سکیں گے۔
صارفین کیلئے ایک اور اہم سہولت کے طور پر ریگولیشن HF 2 کے تحت بینکوں اور ترقیاتی مالیاتی اداروں کو ہدایت کی گئی ہے کہ وہ ہاؤسنگ فنانس کیلئے معیاری اور آسان درخواست فارم متعارف کرائیں۔
مالیاتی اداروں کیلئے یہ بھی لازم ہوگا کہ قرض کی درخواست پر کارروائی کیلئے درکار تمام دستاویزات کی فہرست واضح طور پر فراہم کریں، خواہ درخواست کاغذی صورت میں دی جائے یا ڈیجیٹل ذریعے سے۔
تمام معلومات اور دستاویزی تقاضے اردو اور انگریزی دونوں زبانوں میں فراہم کرنا ہوں گے تاکہ زیادہ سے زیادہ افراد قرض کے طریقہ کار کو آسانی سے سمجھ سکیں۔
سٹیٹ بینک کی یہ اصلاحات پاکستان کی نسبتاً محدود ہاؤسنگ فنانس مارکیٹ میں قرض تک رسائی، استطاعت اور شفافیت بڑھانے کی کوشش کا حصہ ہیں۔
قرض کی مدت بڑھانے، جائیداد کی زیادہ مالیت تک فنانسنگ کی اجازت دینے، غیر رسمی آمدن کو تسلیم کرنے اور درخواست کے طریقہ کار کو آسان بنانے سے زیادہ گھرانے باضابطہ ہاؤسنگ فنانس کے دائرے میں آ سکتے ہیں۔