تاریخ اشاعت: August 6, 2026 - 4:42 PM
UK Housing Market Loses Momentum as Annual Price Growth Slows to 1.8% in July
برطانیہ کی ہاؤسنگ مارکیٹ کی رفتار سست، جولائی میں سالانہ قیمتوں کی شرح نمو 1.8 فیصد رہ گئی
▫️اوسط گھر کی قیمت معمولی اضافے کے بعد 2 لاکھ 77 ہزار 542 پاؤنڈ ہوگئی، شرح سود، توانائی کی قیمتوں اور جغرافیائی سیاسی کشیدگی نے خریداروں کا اعتماد متاثر کیا
London | ReNews International Desk News The United Kingdom’s housing market remained subdued in July 2026, with average property prices recording only a marginal monthly increase as higher borrowing costs, economic uncertainty and geopol...
London | ReNews International Desk News
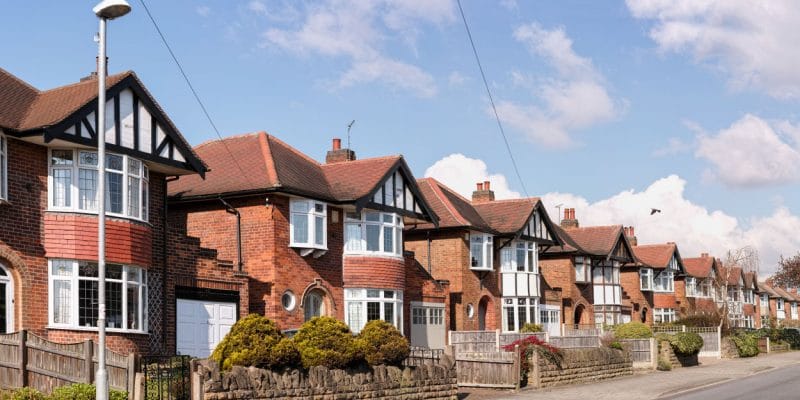
The United Kingdom’s housing market remained subdued in July 2026, with average property prices recording only a marginal monthly increase as higher borrowing costs, economic uncertainty and geopolitical tensions continued to weaken market momentum.
According to Nationwide Building Society’s latest house price report, the value of an average UK home rose by just 0.1% in July compared with the previous month. The average property price increased slightly to £277,542, up from £277,484 in June.
Annual house price growth also slowed to 1.8% in July, compared with 2.2% in June, reflecting weaker buyer confidence and softer market activity across several parts of the country.
Nationwide Chief Economist Robert Gardner said both property prices and housing market activity had remained weak in recent months because of an uncertain economic environment. He noted that geopolitical tensions and renewed conflict involving the United States and Iran had pushed energy prices and market interest rates higher, affecting expectations about inflation and future borrowing costs.
Uncertainty surrounding the Bank of England’s monetary policy has also added pressure to the market. The central bank’s Monetary Policy Committee kept its benchmark interest rate unchanged at 3.75% in July after annual inflation eased to 2.6% in June, down from 2.8% in May.
However, the latest rise in wholesale oil prices has renewed concerns that inflationary pressures could strengthen again. Three members of the nine-member committee voted to increase the Bank Rate to 4%, raising the possibility of tighter monetary policy at the next meeting scheduled for September.
Mortgage lenders usually adjust their rates in anticipation of changes in the Bank Rate. As a result, mortgage costs have already started increasing, creating further affordability challenges for buyers and potentially limiting housing demand during the coming months.
Despite the slowdown, housing industry representatives said stable prices indicated that the market was continuing to find a degree of balance. Propertymark Chief Executive Nathan Emerson said limited housing supply, changing borrowing costs and uneven levels of buyer demand were shaping market conditions.
He added that national figures concealed significant differences between regions, with some more affordable areas performing better than expensive markets where buyers faced greater affordability pressures.
Separate figures released by HM Revenue and Customs showed that approximately 98,700 residential property transactions were completed across the UK in June. This was around 2% higher than in June 2025 and marginally above the total recorded in May 2026.
Property analysts said transaction levels remained resilient but were not particularly strong. They also warned that official transaction data often reflected decisions made several months earlier because property purchases were taking much longer to complete.
Search Acumen Managing Director Andrew Lloyd said June usually produced a seasonal increase in transactions, but the latest figures showed only a modest improvement. He said completion times had become longer than at any point in recent decades, meaning transaction statistics often reflected market sentiment from six to nine months earlier rather than current conditions.
The latest market slowdown follows several months of uneven performance. Annual house price growth stood at 2.2% in June, although prices were unchanged on a monthly basis. In May, annual growth slowed to 1.7%, while average prices fell by 0.6% month on month.
The asking-price market also showed signs of weakening during the early summer. Rightmove reported that average new seller asking prices fell by 0.6% in June, the largest June decline recorded in 14 years. The average asking price dropped to approximately £376,191, as a high number of homes for sale increased competition among sellers.
Property supply remained historically high for the time of year, giving buyers more choice and greater negotiating power. Analysts said sellers were increasingly being forced to set realistic asking prices, particularly for flats and properties in areas where affordability remained stretched.
Regional differences continued to be significant. Property prices in southern England and Wales faced greater downward pressure, while more affordable markets in northern England and Scotland remained comparatively resilient.
The North East and Scotland recorded annual asking-price increases of approximately 3.3% and 3.2%, respectively, while London and parts of southern England experienced weaker conditions.
First-time buyers have benefited to some extent from slower price growth, increased housing supply and a wider selection of high loan-to-value mortgage products. However, higher mortgage rates and broader cost-of-living pressures continue to limit affordability for households that depend heavily on borrowing.
Market data also showed that homeowners generally remain in their properties for significantly longer than tenants. According to the English Housing Survey, people spend an average of around 14 years in the same home.
Homeowners remain in their properties for an average of approximately 24 years, while private renters spend around five years in one residence. People who own their homes outright without a mortgage typically remain in the same property for 30 years or longer.
The outlook for the UK housing market is expected to remain closely linked to inflation, energy prices and future Bank of England interest-rate decisions. A further increase in borrowing costs could weaken buyer demand and place additional pressure on house-price growth.
However, limited housing supply, wage growth and continued demand from households that need to move may help prevent a sharper decline. Analysts believe that the market is more likely to experience a prolonged period of slow growth and uneven regional performance rather than a sudden fall in national property values.
The United Kingdom’s housing market remained subdued in July 2026, with average property prices recording only a marginal monthly increase as higher borrowing costs, economic uncertainty and geopolitical tensions continued to weaken market momentum.
According to Nationwide Building Society’s latest house price report, the value of an average UK home rose by just 0.1% in July compared with the previous month. The average property price increased slightly to £277,542, up from £277,484 in June.
Annual house price growth also slowed to 1.8% in July, compared with 2.2% in June, reflecting weaker buyer confidence and softer market activity across several parts of the country.
Nationwide Chief Economist Robert Gardner said both property prices and housing market activity had remained weak in recent months because of an uncertain economic environment. He noted that geopolitical tensions and renewed conflict involving the United States and Iran had pushed energy prices and market interest rates higher, affecting expectations about inflation and future borrowing costs.
Uncertainty surrounding the Bank of England’s monetary policy has also added pressure to the market. The central bank’s Monetary Policy Committee kept its benchmark interest rate unchanged at 3.75% in July after annual inflation eased to 2.6% in June, down from 2.8% in May.
However, the latest rise in wholesale oil prices has renewed concerns that inflationary pressures could strengthen again. Three members of the nine-member committee voted to increase the Bank Rate to 4%, raising the possibility of tighter monetary policy at the next meeting scheduled for September.
Mortgage lenders usually adjust their rates in anticipation of changes in the Bank Rate. As a result, mortgage costs have already started increasing, creating further affordability challenges for buyers and potentially limiting housing demand during the coming months.
Despite the slowdown, housing industry representatives said stable prices indicated that the market was continuing to find a degree of balance. Propertymark Chief Executive Nathan Emerson said limited housing supply, changing borrowing costs and uneven levels of buyer demand were shaping market conditions.
He added that national figures concealed significant differences between regions, with some more affordable areas performing better than expensive markets where buyers faced greater affordability pressures.
Separate figures released by HM Revenue and Customs showed that approximately 98,700 residential property transactions were completed across the UK in June. This was around 2% higher than in June 2025 and marginally above the total recorded in May 2026.
Property analysts said transaction levels remained resilient but were not particularly strong. They also warned that official transaction data often reflected decisions made several months earlier because property purchases were taking much longer to complete.
Search Acumen Managing Director Andrew Lloyd said June usually produced a seasonal increase in transactions, but the latest figures showed only a modest improvement. He said completion times had become longer than at any point in recent decades, meaning transaction statistics often reflected market sentiment from six to nine months earlier rather than current conditions.
The latest market slowdown follows several months of uneven performance. Annual house price growth stood at 2.2% in June, although prices were unchanged on a monthly basis. In May, annual growth slowed to 1.7%, while average prices fell by 0.6% month on month.
The asking-price market also showed signs of weakening during the early summer. Rightmove reported that average new seller asking prices fell by 0.6% in June, the largest June decline recorded in 14 years. The average asking price dropped to approximately £376,191, as a high number of homes for sale increased competition among sellers.
Property supply remained historically high for the time of year, giving buyers more choice and greater negotiating power. Analysts said sellers were increasingly being forced to set realistic asking prices, particularly for flats and properties in areas where affordability remained stretched.
Regional differences continued to be significant. Property prices in southern England and Wales faced greater downward pressure, while more affordable markets in northern England and Scotland remained comparatively resilient.
The North East and Scotland recorded annual asking-price increases of approximately 3.3% and 3.2%, respectively, while London and parts of southern England experienced weaker conditions.
First-time buyers have benefited to some extent from slower price growth, increased housing supply and a wider selection of high loan-to-value mortgage products. However, higher mortgage rates and broader cost-of-living pressures continue to limit affordability for households that depend heavily on borrowing.
Market data also showed that homeowners generally remain in their properties for significantly longer than tenants. According to the English Housing Survey, people spend an average of around 14 years in the same home.
Homeowners remain in their properties for an average of approximately 24 years, while private renters spend around five years in one residence. People who own their homes outright without a mortgage typically remain in the same property for 30 years or longer.
The outlook for the UK housing market is expected to remain closely linked to inflation, energy prices and future Bank of England interest-rate decisions. A further increase in borrowing costs could weaken buyer demand and place additional pressure on house-price growth.
However, limited housing supply, wage growth and continued demand from households that need to move may help prevent a sharper decline. Analysts believe that the market is more likely to experience a prolonged period of slow growth and uneven regional performance rather than a sudden fall in national property values.
لندن | ری نیوز انٹرنیشنل ڈیسک نیوز
برطانیہ کی ہاؤسنگ مارکیٹ جولائی 2026 میں سست روی کا شکار رہی، جہاں اوسط جائیداد کی قیمتوں میں ماہانہ بنیاد پر نہایت معمولی اضافہ ریکارڈ کیا گیا۔ بلند قرضہ جاتی اخراجات، معاشی غیر یقینی صورتحال اور جغرافیائی سیاسی کشیدگی نے مارکیٹ کی رفتار اور خریداروں کے اعتماد کو متاثر کیا۔
نیشن وائیڈ بلڈنگ سوسائٹی کی تازہ ہاؤس پرائس رپورٹ کے مطابق جولائی میں برطانیہ کے ایک اوسط گھر کی قیمت میں گزشتہ ماہ کے مقابلے میں صرف 0.1 فیصد اضافہ ہوا۔ اوسط قیمت جون کے 2 لاکھ 77 ہزار 484 پاؤنڈ سے بڑھ کر 2 لاکھ 77 ہزار 542 پاؤنڈ ہوگئی۔
سالانہ بنیاد پر بھی گھروں کی قیمتوں میں اضافے کی رفتار کم ہوکر 1.8 فیصد رہ گئی، جو جون میں 2.2 فیصد تھی۔ یہ صورتحال ملک کے مختلف حصوں میں خریداروں کے کمزور اعتماد اور محدود مارکیٹ سرگرمی کی عکاسی کرتی ہے۔
نیشن وائیڈ کے چیف اکانومسٹ رابرٹ گارڈنر کے مطابق حالیہ مہینوں میں جائیدادوں کی قیمتیں اور ہاؤسنگ مارکیٹ کی سرگرمیاں دونوں نرم رہی ہیں، جس کی بنیادی وجہ غیر یقینی معاشی ماحول ہے۔ ان کا کہنا تھا کہ جغرافیائی سیاسی کشیدگی اور امریکا و ایران کے درمیان دوبارہ بڑھنے والے تنازع نے توانائی کی قیمتوں اور مارکیٹ شرح سود پر دباؤ بڑھایا ہے، جس سے مہنگائی اور مستقبل کے قرضہ جاتی اخراجات سے متعلق توقعات متاثر ہوئی ہیں۔
بینک آف انگلینڈ کی مانیٹری پالیسی سے متعلق غیر یقینی صورتحال نے بھی مارکیٹ پر دباؤ برقرار رکھا۔ مرکزی بینک کی مانیٹری پالیسی کمیٹی نے جولائی میں بنیادی شرح سود 3.75 فیصد پر برقرار رکھی، جبکہ جون میں سالانہ مہنگائی کی شرح کم ہوکر 2.6 فیصد ہوگئی تھی، جو مئی میں 2.8 فیصد تھی۔
تاہم عالمی منڈی میں تیل کی قیمتوں میں تازہ اضافے نے مہنگائی کے دوبارہ بڑھنے کے خدشات پیدا کردیے ہیں۔ نو رکنی کمیٹی کے تین ارکان نے شرح سود بڑھا کر 4 فیصد کرنے کے حق میں ووٹ دیا، جس سے آئندہ اجلاس میں مالیاتی پالیسی مزید سخت کیے جانے کا امکان ظاہر کیا جارہا ہے۔
مارگیج فراہم کرنے والے ادارے عموماً بینک ریٹ میں ممکنہ تبدیلیوں کو مدنظر رکھتے ہوئے اپنی شرحیں طے کرتے ہیں۔ اسی وجہ سے مارگیج اخراجات پہلے ہی بڑھنا شروع ہوگئے ہیں، جس سے خریداروں کی قوت خرید متاثر ہورہی ہے اور آئندہ مہینوں میں ہاؤسنگ کی طلب مزید کم ہوسکتی ہے۔
مارکیٹ کی سست روی کے باوجود پراپرٹی شعبے کے نمائندوں کا کہنا ہے کہ قیمتوں میں استحکام اس بات کی علامت ہے کہ مارکیٹ کسی حد تک توازن کی جانب بڑھ رہی ہے۔ پراپرٹی مارک کے چیف ایگزیکٹو نیتھن ایمرسن کے مطابق محدود ہاؤسنگ سپلائی، قرضہ جاتی اخراجات میں تبدیلی اور مختلف علاقوں میں طلب کے غیر مساوی رجحانات مارکیٹ کی موجودہ صورتحال کو تشکیل دے رہے ہیں۔
انہوں نے کہا کہ قومی سطح کے اعدادوشمار مختلف علاقوں کے نمایاں فرق کو مکمل طور پر ظاہر نہیں کرتے۔ نسبتاً کم قیمت والے علاقوں میں مارکیٹ کی کارکردگی بہتر ہے، جبکہ مہنگے علاقوں میں خریداروں کو زیادہ شدید مالی دباؤ کا سامنا ہے۔
ایچ ایم ریونیو اینڈ کسٹمز کے الگ اعدادوشمار کے مطابق جون میں برطانیہ بھر میں تقریباً 98 ہزار 700 رہائشی جائیدادوں کے لین دین مکمل ہوئے۔ یہ تعداد جون 2025 کے مقابلے میں تقریباً 2 فیصد زیادہ اور مئی 2026 کے مقابلے میں معمولی بلند رہی۔
پراپرٹی تجزیہ کاروں کے مطابق لین دین کی سطح نسبتاً مستحکم ضرور رہی، تاہم اسے غیرمعمولی طور پر مضبوط قرار نہیں دیا جاسکتا۔ ماہرین نے یہ بھی خبردار کیا کہ خرید و فروخت کے معاملات مکمل ہونے میں زیادہ وقت لگنے کے باعث سرکاری اعدادوشمار اکثر کئی ماہ پرانے فیصلوں کی عکاسی کرتے ہیں۔
پراپرٹی ڈیٹا فرم سرچ اکیومن کے منیجنگ ڈائریکٹر اینڈریو لائیڈ کے مطابق جون میں عموماً موسمی بنیاد پر لین دین میں اضافہ ہوتا ہے، تاہم تازہ اعدادوشمار میں صرف معمولی بہتری دکھائی دی۔ ان کا کہنا تھا کہ جائیدادوں کے معاملات مکمل ہونے میں کئی دہائیوں کے مقابلے میں زیادہ وقت لگ رہا ہے، اس لیے موجودہ اعدادوشمار آج کی مارکیٹ کے بجائے چھ سے نو ماہ قبل کے رجحانات کی تصویر پیش کرتے ہیں۔
برطانوی ہاؤسنگ مارکیٹ کی حالیہ سست روی کئی ماہ سے جاری غیر متوازن کارکردگی کا تسلسل ہے۔ جون میں سالانہ قیمتوں کی شرح نمو 2.2 فیصد تھی، اگرچہ ماہانہ بنیاد پر قیمتیں تقریباً مستحکم رہیں۔ مئی میں سالانہ شرح نمو کم ہوکر 1.7 فیصد رہ گئی تھی، جبکہ ماہانہ بنیاد پر اوسط قیمتوں میں 0.6 فیصد کمی ریکارڈ کی گئی۔
ابتدائی موسم گرما کے دوران فروخت کے لیے پیش کی جانے والی جائیدادوں کی قیمتوں میں بھی کمزوری دیکھی گئی۔ رائٹ موو کے مطابق جون میں نئے فروخت کنندگان کی اوسط مطلوبہ قیمت میں 0.6 فیصد کمی ہوئی، جو گزشتہ 14 برس میں جون کی سب سے بڑی کمی تھی۔ اوسط مطلوبہ قیمت کم ہوکر تقریباً 3 لاکھ 76 ہزار 191 پاؤنڈ رہ گئی، کیونکہ مارکیٹ میں جائیدادوں کی زیادہ تعداد نے فروخت کنندگان کے درمیان مقابلہ بڑھا دیا۔
اس موسم کے اعتبار سے جائیدادوں کی دستیابی تاریخی طور پر بلند سطح پر رہی، جس سے خریداروں کو زیادہ انتخاب اور قیمت پر بہتر سودے بازی کا موقع ملا۔ تجزیہ کاروں کے مطابق خاص طور پر فلیٹس اور مہنگے علاقوں میں جائیدادیں فروخت کرنے والوں کو زیادہ حقیقت پسندانہ قیمتیں مقرر کرنا پڑرہی ہیں۔
علاقائی فرق بھی نمایاں رہا۔ جنوبی انگلینڈ اور ویلز میں قیمتوں پر زیادہ دباؤ دیکھا گیا، جبکہ شمالی انگلینڈ اور اسکاٹ لینڈ کے نسبتاً کم قیمت والے علاقوں نے بہتر کارکردگی دکھائی۔
نارتھ ایسٹ اور اسکاٹ لینڈ میں سالانہ مطلوبہ قیمتوں میں بالترتیب تقریباً 3.3 فیصد اور 3.2 فیصد اضافہ ریکارڈ کیا گیا، جبکہ لندن اور جنوبی انگلینڈ کے کئی علاقوں میں مارکیٹ نسبتاً کمزور رہی۔
پہلی مرتبہ گھر خریدنے والوں کو سست قیمتوں، زیادہ ہاؤسنگ سپلائی اور ہائی لون ٹو ویلیو مارگیج مصنوعات کی وسیع دستیابی سے کسی حد تک فائدہ ہوا ہے۔ تاہم بلند مارگیج شرحیں اور روزمرہ اخراجات میں اضافہ اب بھی ایسے خریداروں کے لیے بڑا چیلنج ہے جو زیادہ تر قرض پر انحصار کرتے ہیں۔
مارکیٹ کے اعدادوشمار کے مطابق گھر کے مالکان عموماً کرایہ داروں کے مقابلے میں ایک ہی جائیداد میں زیادہ طویل عرصہ قیام کرتے ہیں۔ انگلش ہاؤسنگ سروے کے مطابق لوگ اوسطاً تقریباً 14 سال ایک ہی گھر میں رہتے ہیں۔
گھر کے مالکان کسی ایک جائیداد میں اوسطاً تقریباً 24 سال قیام کرتے ہیں، جبکہ نجی کرایہ دار ایک ہی رہائش میں اوسطاً پانچ سال گزارتے ہیں۔ ایسے افراد جو بغیر مارگیج کے اپنے گھر کے مکمل مالک ہوں، عموماً ایک ہی جائیداد میں 30 سال یا اس سے زیادہ عرصہ رہتے ہیں۔
برطانیہ کی ہاؤسنگ مارکیٹ کا مستقبل مہنگائی، توانائی کی قیمتوں اور بینک آف انگلینڈ کے آئندہ شرح سود کے فیصلوں سے قریب سے منسلک رہے گا۔ قرضہ جاتی اخراجات میں مزید اضافہ خریداروں کی طلب کو کم اور قیمتوں کی شرح نمو کو مزید محدود کرسکتا ہے۔
تاہم محدود ہاؤسنگ سپلائی، اجرتوں میں اضافہ اور ضروری وجوہات کی بنا پر گھر تبدیل کرنے والے خاندانوں کی طلب مارکیٹ کو شدید گراوٹ سے محفوظ رکھ سکتی ہے۔ ماہرین کے مطابق قومی سطح پر قیمتوں میں اچانک بڑی کمی کے بجائے سست رفتار نمو اور مختلف علاقوں میں غیر مساوی کارکردگی کا رجحان برقرار رہنے کا امکان زیادہ ہ
برطانیہ کی ہاؤسنگ مارکیٹ جولائی 2026 میں سست روی کا شکار رہی، جہاں اوسط جائیداد کی قیمتوں میں ماہانہ بنیاد پر نہایت معمولی اضافہ ریکارڈ کیا گیا۔ بلند قرضہ جاتی اخراجات، معاشی غیر یقینی صورتحال اور جغرافیائی سیاسی کشیدگی نے مارکیٹ کی رفتار اور خریداروں کے اعتماد کو متاثر کیا۔
نیشن وائیڈ بلڈنگ سوسائٹی کی تازہ ہاؤس پرائس رپورٹ کے مطابق جولائی میں برطانیہ کے ایک اوسط گھر کی قیمت میں گزشتہ ماہ کے مقابلے میں صرف 0.1 فیصد اضافہ ہوا۔ اوسط قیمت جون کے 2 لاکھ 77 ہزار 484 پاؤنڈ سے بڑھ کر 2 لاکھ 77 ہزار 542 پاؤنڈ ہوگئی۔
سالانہ بنیاد پر بھی گھروں کی قیمتوں میں اضافے کی رفتار کم ہوکر 1.8 فیصد رہ گئی، جو جون میں 2.2 فیصد تھی۔ یہ صورتحال ملک کے مختلف حصوں میں خریداروں کے کمزور اعتماد اور محدود مارکیٹ سرگرمی کی عکاسی کرتی ہے۔
نیشن وائیڈ کے چیف اکانومسٹ رابرٹ گارڈنر کے مطابق حالیہ مہینوں میں جائیدادوں کی قیمتیں اور ہاؤسنگ مارکیٹ کی سرگرمیاں دونوں نرم رہی ہیں، جس کی بنیادی وجہ غیر یقینی معاشی ماحول ہے۔ ان کا کہنا تھا کہ جغرافیائی سیاسی کشیدگی اور امریکا و ایران کے درمیان دوبارہ بڑھنے والے تنازع نے توانائی کی قیمتوں اور مارکیٹ شرح سود پر دباؤ بڑھایا ہے، جس سے مہنگائی اور مستقبل کے قرضہ جاتی اخراجات سے متعلق توقعات متاثر ہوئی ہیں۔
بینک آف انگلینڈ کی مانیٹری پالیسی سے متعلق غیر یقینی صورتحال نے بھی مارکیٹ پر دباؤ برقرار رکھا۔ مرکزی بینک کی مانیٹری پالیسی کمیٹی نے جولائی میں بنیادی شرح سود 3.75 فیصد پر برقرار رکھی، جبکہ جون میں سالانہ مہنگائی کی شرح کم ہوکر 2.6 فیصد ہوگئی تھی، جو مئی میں 2.8 فیصد تھی۔
تاہم عالمی منڈی میں تیل کی قیمتوں میں تازہ اضافے نے مہنگائی کے دوبارہ بڑھنے کے خدشات پیدا کردیے ہیں۔ نو رکنی کمیٹی کے تین ارکان نے شرح سود بڑھا کر 4 فیصد کرنے کے حق میں ووٹ دیا، جس سے آئندہ اجلاس میں مالیاتی پالیسی مزید سخت کیے جانے کا امکان ظاہر کیا جارہا ہے۔
مارگیج فراہم کرنے والے ادارے عموماً بینک ریٹ میں ممکنہ تبدیلیوں کو مدنظر رکھتے ہوئے اپنی شرحیں طے کرتے ہیں۔ اسی وجہ سے مارگیج اخراجات پہلے ہی بڑھنا شروع ہوگئے ہیں، جس سے خریداروں کی قوت خرید متاثر ہورہی ہے اور آئندہ مہینوں میں ہاؤسنگ کی طلب مزید کم ہوسکتی ہے۔
مارکیٹ کی سست روی کے باوجود پراپرٹی شعبے کے نمائندوں کا کہنا ہے کہ قیمتوں میں استحکام اس بات کی علامت ہے کہ مارکیٹ کسی حد تک توازن کی جانب بڑھ رہی ہے۔ پراپرٹی مارک کے چیف ایگزیکٹو نیتھن ایمرسن کے مطابق محدود ہاؤسنگ سپلائی، قرضہ جاتی اخراجات میں تبدیلی اور مختلف علاقوں میں طلب کے غیر مساوی رجحانات مارکیٹ کی موجودہ صورتحال کو تشکیل دے رہے ہیں۔
انہوں نے کہا کہ قومی سطح کے اعدادوشمار مختلف علاقوں کے نمایاں فرق کو مکمل طور پر ظاہر نہیں کرتے۔ نسبتاً کم قیمت والے علاقوں میں مارکیٹ کی کارکردگی بہتر ہے، جبکہ مہنگے علاقوں میں خریداروں کو زیادہ شدید مالی دباؤ کا سامنا ہے۔
ایچ ایم ریونیو اینڈ کسٹمز کے الگ اعدادوشمار کے مطابق جون میں برطانیہ بھر میں تقریباً 98 ہزار 700 رہائشی جائیدادوں کے لین دین مکمل ہوئے۔ یہ تعداد جون 2025 کے مقابلے میں تقریباً 2 فیصد زیادہ اور مئی 2026 کے مقابلے میں معمولی بلند رہی۔
پراپرٹی تجزیہ کاروں کے مطابق لین دین کی سطح نسبتاً مستحکم ضرور رہی، تاہم اسے غیرمعمولی طور پر مضبوط قرار نہیں دیا جاسکتا۔ ماہرین نے یہ بھی خبردار کیا کہ خرید و فروخت کے معاملات مکمل ہونے میں زیادہ وقت لگنے کے باعث سرکاری اعدادوشمار اکثر کئی ماہ پرانے فیصلوں کی عکاسی کرتے ہیں۔
پراپرٹی ڈیٹا فرم سرچ اکیومن کے منیجنگ ڈائریکٹر اینڈریو لائیڈ کے مطابق جون میں عموماً موسمی بنیاد پر لین دین میں اضافہ ہوتا ہے، تاہم تازہ اعدادوشمار میں صرف معمولی بہتری دکھائی دی۔ ان کا کہنا تھا کہ جائیدادوں کے معاملات مکمل ہونے میں کئی دہائیوں کے مقابلے میں زیادہ وقت لگ رہا ہے، اس لیے موجودہ اعدادوشمار آج کی مارکیٹ کے بجائے چھ سے نو ماہ قبل کے رجحانات کی تصویر پیش کرتے ہیں۔
برطانوی ہاؤسنگ مارکیٹ کی حالیہ سست روی کئی ماہ سے جاری غیر متوازن کارکردگی کا تسلسل ہے۔ جون میں سالانہ قیمتوں کی شرح نمو 2.2 فیصد تھی، اگرچہ ماہانہ بنیاد پر قیمتیں تقریباً مستحکم رہیں۔ مئی میں سالانہ شرح نمو کم ہوکر 1.7 فیصد رہ گئی تھی، جبکہ ماہانہ بنیاد پر اوسط قیمتوں میں 0.6 فیصد کمی ریکارڈ کی گئی۔
ابتدائی موسم گرما کے دوران فروخت کے لیے پیش کی جانے والی جائیدادوں کی قیمتوں میں بھی کمزوری دیکھی گئی۔ رائٹ موو کے مطابق جون میں نئے فروخت کنندگان کی اوسط مطلوبہ قیمت میں 0.6 فیصد کمی ہوئی، جو گزشتہ 14 برس میں جون کی سب سے بڑی کمی تھی۔ اوسط مطلوبہ قیمت کم ہوکر تقریباً 3 لاکھ 76 ہزار 191 پاؤنڈ رہ گئی، کیونکہ مارکیٹ میں جائیدادوں کی زیادہ تعداد نے فروخت کنندگان کے درمیان مقابلہ بڑھا دیا۔
اس موسم کے اعتبار سے جائیدادوں کی دستیابی تاریخی طور پر بلند سطح پر رہی، جس سے خریداروں کو زیادہ انتخاب اور قیمت پر بہتر سودے بازی کا موقع ملا۔ تجزیہ کاروں کے مطابق خاص طور پر فلیٹس اور مہنگے علاقوں میں جائیدادیں فروخت کرنے والوں کو زیادہ حقیقت پسندانہ قیمتیں مقرر کرنا پڑرہی ہیں۔
علاقائی فرق بھی نمایاں رہا۔ جنوبی انگلینڈ اور ویلز میں قیمتوں پر زیادہ دباؤ دیکھا گیا، جبکہ شمالی انگلینڈ اور اسکاٹ لینڈ کے نسبتاً کم قیمت والے علاقوں نے بہتر کارکردگی دکھائی۔
نارتھ ایسٹ اور اسکاٹ لینڈ میں سالانہ مطلوبہ قیمتوں میں بالترتیب تقریباً 3.3 فیصد اور 3.2 فیصد اضافہ ریکارڈ کیا گیا، جبکہ لندن اور جنوبی انگلینڈ کے کئی علاقوں میں مارکیٹ نسبتاً کمزور رہی۔
پہلی مرتبہ گھر خریدنے والوں کو سست قیمتوں، زیادہ ہاؤسنگ سپلائی اور ہائی لون ٹو ویلیو مارگیج مصنوعات کی وسیع دستیابی سے کسی حد تک فائدہ ہوا ہے۔ تاہم بلند مارگیج شرحیں اور روزمرہ اخراجات میں اضافہ اب بھی ایسے خریداروں کے لیے بڑا چیلنج ہے جو زیادہ تر قرض پر انحصار کرتے ہیں۔
مارکیٹ کے اعدادوشمار کے مطابق گھر کے مالکان عموماً کرایہ داروں کے مقابلے میں ایک ہی جائیداد میں زیادہ طویل عرصہ قیام کرتے ہیں۔ انگلش ہاؤسنگ سروے کے مطابق لوگ اوسطاً تقریباً 14 سال ایک ہی گھر میں رہتے ہیں۔
گھر کے مالکان کسی ایک جائیداد میں اوسطاً تقریباً 24 سال قیام کرتے ہیں، جبکہ نجی کرایہ دار ایک ہی رہائش میں اوسطاً پانچ سال گزارتے ہیں۔ ایسے افراد جو بغیر مارگیج کے اپنے گھر کے مکمل مالک ہوں، عموماً ایک ہی جائیداد میں 30 سال یا اس سے زیادہ عرصہ رہتے ہیں۔
برطانیہ کی ہاؤسنگ مارکیٹ کا مستقبل مہنگائی، توانائی کی قیمتوں اور بینک آف انگلینڈ کے آئندہ شرح سود کے فیصلوں سے قریب سے منسلک رہے گا۔ قرضہ جاتی اخراجات میں مزید اضافہ خریداروں کی طلب کو کم اور قیمتوں کی شرح نمو کو مزید محدود کرسکتا ہے۔
تاہم محدود ہاؤسنگ سپلائی، اجرتوں میں اضافہ اور ضروری وجوہات کی بنا پر گھر تبدیل کرنے والے خاندانوں کی طلب مارکیٹ کو شدید گراوٹ سے محفوظ رکھ سکتی ہے۔ ماہرین کے مطابق قومی سطح پر قیمتوں میں اچانک بڑی کمی کے بجائے سست رفتار نمو اور مختلف علاقوں میں غیر مساوی کارکردگی کا رجحان برقرار رہنے کا امکان زیادہ ہ