تاریخ اشاعت: October 1, 2026 - 2:01 PM
FBR to Seal Businesses Not Integrated With Monitoring System
ایف بی آر مانیٹرنگ سسٹم سے منسلک نہ ہونے والے کاروبار سیل کرنے کا فیصلہ
▫️ پروڈکشن مانیٹرنگ، ویڈیو سرویلنس یا ڈیجیٹل آئی سسٹم کی تنصیب لازم، انضمام کیلئے الیکٹرانک آلات پر سرمایہ کاری کا 10 فیصد ٹیکس کریڈٹ بھی دیا جائے گا
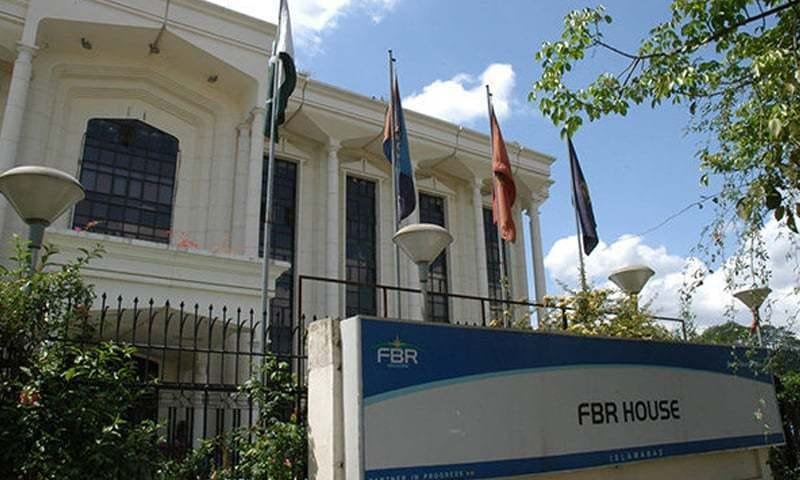
اسلام آباد | ری نیوز پاکستانوفاقی حکومت نے ایف بی آر کے کمپیوٹرائزڈ نظام سے کاروباری اداروں کے انضمام کیلئے مانیٹرنگ کا دائرہ مزید سخت کرتے ہوئے سسٹم سے منسلک نہ ہونے والے رجسٹرڈ کاروباری مراکز کے خلاف کارروائی کا طریقہ کار وضع کردیا ہے۔
Islamabad | ReNews Pakistan
The Federal Board of Revenue (FBR) has moved to strengthen enforcement against registered businesses that fail to integrate with its computerized monitoring system. Under amendments to the Sales Tax Rules 2006, businesses required to provide real time production monitoring or recording and reporting of sales and receipts will have to install the prescribed electronic monitoring, video surveillance or digital eye systems and integrate them with the FBR system.
Under the Finance Act 2026 27, businesses required under the relevant tax laws to integrate with the FBR computerized system for real time production monitoring or for recording and reporting sales or receipts will be entitled to a 10% tax credit on eligible investment made exclusively for the purchase, acquisition, installation or implementation of the required equipment, hardware, software and other electronic components.
The Finance Bill 2026 specifies that the tax credit will be available for the tax year in which the electronic resource is installed, integrated and configured with the FBR computerized system. The credit will be calculated at 10% of the amount actually invested in the eligible electronic resource, while operation and maintenance expenses will not qualify for the credit.
The enforcement framework provides for action against registered businesses that fail to comply with the integration requirements. Business premises may be sealed where the prescribed monitoring and integration requirements are not fulfilled, with police assistance available where required.
Under the procedure, an Assistant Commissioner Inland Revenue or an officer of higher rank may submit a written report to the concerned Commissioner Inland Revenue regarding non compliance by a business. The Commissioner may initiate an inquiry on the basis of the report and, after completing the inquiry, forward the findings to the Chief Commissioner.
The Chief Commissioner will then issue a written order on whether the business premises should be sealed. Depending on the circumstances, the entire business premises or only a specified portion may be sealed under the procedure.
The electronic monitoring framework is designed to enable real time collection and transmission of production data to the FBR system. Existing Sales Tax Rules provide for the use of video cameras, sensors and other approved equipment for monitoring production, transmitting data to the FBR central control room and maintaining production records.
The FBR has already introduced electronic production monitoring through video analytics in several specified sectors. In 2026, the Board issued Sales Tax General Orders covering electronic monitoring of production in sectors including tiles, bottled water, packaged juices, packaged milk and aerated beverages.
The FBR has stated that electronic monitoring is intended to improve tax compliance, reduce under reporting and strengthen documentation of production and sales. Its existing framework also provides for penalties, legal proceedings and sealing of premises in cases of non compliance with prescribed electronic monitoring requirements.
For businesses required to integrate with the FBR system, the 10% tax credit provides a tax adjustment mechanism against eligible investment in the technology needed for compliance. At the same time, failure to meet mandatory integration requirements can lead to enforcement action, including sealing of all or part of the business premises under the prescribed procedure.
The Federal Board of Revenue (FBR) has moved to strengthen enforcement against registered businesses that fail to integrate with its computerized monitoring system. Under amendments to the Sales Tax Rules 2006, businesses required to provide real time production monitoring or recording and reporting of sales and receipts will have to install the prescribed electronic monitoring, video surveillance or digital eye systems and integrate them with the FBR system.
Under the Finance Act 2026 27, businesses required under the relevant tax laws to integrate with the FBR computerized system for real time production monitoring or for recording and reporting sales or receipts will be entitled to a 10% tax credit on eligible investment made exclusively for the purchase, acquisition, installation or implementation of the required equipment, hardware, software and other electronic components.
The Finance Bill 2026 specifies that the tax credit will be available for the tax year in which the electronic resource is installed, integrated and configured with the FBR computerized system. The credit will be calculated at 10% of the amount actually invested in the eligible electronic resource, while operation and maintenance expenses will not qualify for the credit.
The enforcement framework provides for action against registered businesses that fail to comply with the integration requirements. Business premises may be sealed where the prescribed monitoring and integration requirements are not fulfilled, with police assistance available where required.
Under the procedure, an Assistant Commissioner Inland Revenue or an officer of higher rank may submit a written report to the concerned Commissioner Inland Revenue regarding non compliance by a business. The Commissioner may initiate an inquiry on the basis of the report and, after completing the inquiry, forward the findings to the Chief Commissioner.
The Chief Commissioner will then issue a written order on whether the business premises should be sealed. Depending on the circumstances, the entire business premises or only a specified portion may be sealed under the procedure.
The electronic monitoring framework is designed to enable real time collection and transmission of production data to the FBR system. Existing Sales Tax Rules provide for the use of video cameras, sensors and other approved equipment for monitoring production, transmitting data to the FBR central control room and maintaining production records.
The FBR has already introduced electronic production monitoring through video analytics in several specified sectors. In 2026, the Board issued Sales Tax General Orders covering electronic monitoring of production in sectors including tiles, bottled water, packaged juices, packaged milk and aerated beverages.
The FBR has stated that electronic monitoring is intended to improve tax compliance, reduce under reporting and strengthen documentation of production and sales. Its existing framework also provides for penalties, legal proceedings and sealing of premises in cases of non compliance with prescribed electronic monitoring requirements.
For businesses required to integrate with the FBR system, the 10% tax credit provides a tax adjustment mechanism against eligible investment in the technology needed for compliance. At the same time, failure to meet mandatory integration requirements can lead to enforcement action, including sealing of all or part of the business premises under the prescribed procedure.
اسلام آباد | ری نیوز پاکستان
وفاقی حکومت نے ایف بی آر کے کمپیوٹرائزڈ نظام سے کاروباری اداروں کے انضمام کیلئے مانیٹرنگ کا دائرہ مزید سخت کرتے ہوئے سسٹم سے منسلک نہ ہونے والے رجسٹرڈ کاروباری مراکز کے خلاف کارروائی کا طریقہ کار وضع کردیا ہے۔ سیلز ٹیکس رولز 2006 میں ترامیم کے تحت متعلقہ کاروباری اداروں کیلئے پروڈکشن مانیٹرنگ، ویڈیو سرویلنس یا ڈیجیٹل آئی سسٹم کی تنصیب اور ایف بی آر کے کمپیوٹرائزڈ نظام سے انضمام ضروری ہوگا۔
فنانس ایکٹ27-2026 کے تحت ایسے کاروباری ادارے جو ریئل ٹائم پیداوار کی نگرانی یا فروخت اور وصولیوں کی ریکارڈنگ و رپورٹنگ کیلئے ایف بی آر کے کمپیوٹرائزڈ نظام سے انضمام کے پابند ہیں، انہیں اس مقصد کیلئے درکار الیکٹرانک آلات، ہارڈویئر، سافٹ ویئر اور دیگر الیکٹرانک اجزا کی خریداری، تنصیب اور تنفیذ پر کی گئی سرمایہ کاری کا 10 فیصد ٹیکس کریڈٹ دیا جائے گا۔ ایف بی آر کے فنانس بل 2026 کے مطابق یہ ٹیکس کریڈٹ اس ٹیکس سال میں دستیاب ہوگا جس میں الیکٹرانک نظام نصب، مربوط اور ایف بی آر کے کمپیوٹرائزڈ نظام کے ساتھ کنفیگر کیا جائے۔
ایف بی آر کے موجودہ قواعد میں بھی مخصوص شعبوں کی پیداوار کی الیکٹرانک مانیٹرنگ کیلئے ویڈیو کیمروں، سینسرز اور دیگر آلات کے ذریعے ریئل ٹائم ڈیٹا حاصل کرنے، اسے ایف بی آر کے مرکزی کنٹرول روم تک منتقل کرنے اور پیداوار کا ڈیٹا محفوظ کرنے کا طریقہ کار موجود ہے۔
نئے انتظام کے تحت ایف بی آر کے مانیٹرنگ سسٹم سے منسلک نہ ہونے والے رجسٹرڈ کاروباری مراکز کے خلاف سیل کرنے کی کارروائی کی جا سکے گی۔ ضرورت پڑنے پر کاروباری مقام سیل کرنے کیلئے پولیس کی مدد بھی حاصل کی جا سکے گی۔
طے شدہ طریقہ کار کے مطابق اسسٹنٹ کمشنر ان لینڈ ریونیو یا اس سے اوپر کا افسر کاروباری ادارے کی عدم تعمیل سے متعلق تحریری رپورٹ متعلقہ کمشنر ان لینڈ ریونیو کو دے گا۔ کمشنر رپورٹ کی بنیاد پر معاملے کی انکوائری کر سکے گا اور انکوائری مکمل ہونے کے بعد رپورٹ چیف کمشنر کو ارسال کی جائے گی۔
چیف کمشنر انکوائری رپورٹ کا جائزہ لینے کے بعد کاروباری مرکز کو سیل کرنے یا نہ کرنے کے حوالے سے تحریری حکم جاری کرے گا۔ قواعد کے تحت ضرورت کے مطابق کاروباری مقام کا مکمل حصہ یا صرف مخصوص حصہ بھی سیل کیا جا سکے گا۔
ایف بی آر کے مطابق الیکٹرانک مانیٹرنگ کا بنیادی مقصد پیداوار، فروخت اور متعلقہ کاروباری سرگرمیوں کے ڈیٹا کو ریئل ٹائم بنیادوں پر ریکارڈ اور رپورٹ کرنا ہے تاکہ ٹیکس نظام میں دستاویز بندی اور شفافیت بہتر بنائی جا سکے۔ ایف بی آر پہلے ہی مختلف شعبوں میں ویڈیو اینالیٹکس اور الیکٹرانک مانیٹرنگ کے نظام متعارف کرا چکا ہے۔
ایف بی آر کی جانب سے مخصوص شعبوں میں الیکٹرانک مانیٹرنگ کیلئے عدم تعمیل کی صورت میں جرمانوں اور دیگر قانونی کارروائی کے ساتھ کاروباری مقامات سیل کرنے کی گنجائش بھی موجود ہے۔
دوسری جانب کاروباری اداروں کیلئے 10 فیصد ٹیکس کریڈٹ کا اقدام مانیٹرنگ اور انضمام کیلئے درکار ٹیکنالوجی پر ہونے والی سرمایہ کاری کی لاگت کو جزوی طور پر ٹیکس کریڈٹ کے ذریعے ایڈجسٹ کرنے کا طریقہ فراہم کرتا ہے۔ تاہم یہ سہولت صرف متعلقہ الیکٹرانک وسائل کی خریداری، تنصیب اور تنفیذ پر ہونے والی اہل سرمایہ کاری کیلئے ہے جبکہ آپریشن اور مینٹیننس کے اخراجات اس کریڈٹ میں شامل نہیں ہوں گے۔
وفاقی حکومت نے ایف بی آر کے کمپیوٹرائزڈ نظام سے کاروباری اداروں کے انضمام کیلئے مانیٹرنگ کا دائرہ مزید سخت کرتے ہوئے سسٹم سے منسلک نہ ہونے والے رجسٹرڈ کاروباری مراکز کے خلاف کارروائی کا طریقہ کار وضع کردیا ہے۔ سیلز ٹیکس رولز 2006 میں ترامیم کے تحت متعلقہ کاروباری اداروں کیلئے پروڈکشن مانیٹرنگ، ویڈیو سرویلنس یا ڈیجیٹل آئی سسٹم کی تنصیب اور ایف بی آر کے کمپیوٹرائزڈ نظام سے انضمام ضروری ہوگا۔
فنانس ایکٹ27-2026 کے تحت ایسے کاروباری ادارے جو ریئل ٹائم پیداوار کی نگرانی یا فروخت اور وصولیوں کی ریکارڈنگ و رپورٹنگ کیلئے ایف بی آر کے کمپیوٹرائزڈ نظام سے انضمام کے پابند ہیں، انہیں اس مقصد کیلئے درکار الیکٹرانک آلات، ہارڈویئر، سافٹ ویئر اور دیگر الیکٹرانک اجزا کی خریداری، تنصیب اور تنفیذ پر کی گئی سرمایہ کاری کا 10 فیصد ٹیکس کریڈٹ دیا جائے گا۔ ایف بی آر کے فنانس بل 2026 کے مطابق یہ ٹیکس کریڈٹ اس ٹیکس سال میں دستیاب ہوگا جس میں الیکٹرانک نظام نصب، مربوط اور ایف بی آر کے کمپیوٹرائزڈ نظام کے ساتھ کنفیگر کیا جائے۔
ایف بی آر کے موجودہ قواعد میں بھی مخصوص شعبوں کی پیداوار کی الیکٹرانک مانیٹرنگ کیلئے ویڈیو کیمروں، سینسرز اور دیگر آلات کے ذریعے ریئل ٹائم ڈیٹا حاصل کرنے، اسے ایف بی آر کے مرکزی کنٹرول روم تک منتقل کرنے اور پیداوار کا ڈیٹا محفوظ کرنے کا طریقہ کار موجود ہے۔
نئے انتظام کے تحت ایف بی آر کے مانیٹرنگ سسٹم سے منسلک نہ ہونے والے رجسٹرڈ کاروباری مراکز کے خلاف سیل کرنے کی کارروائی کی جا سکے گی۔ ضرورت پڑنے پر کاروباری مقام سیل کرنے کیلئے پولیس کی مدد بھی حاصل کی جا سکے گی۔
طے شدہ طریقہ کار کے مطابق اسسٹنٹ کمشنر ان لینڈ ریونیو یا اس سے اوپر کا افسر کاروباری ادارے کی عدم تعمیل سے متعلق تحریری رپورٹ متعلقہ کمشنر ان لینڈ ریونیو کو دے گا۔ کمشنر رپورٹ کی بنیاد پر معاملے کی انکوائری کر سکے گا اور انکوائری مکمل ہونے کے بعد رپورٹ چیف کمشنر کو ارسال کی جائے گی۔
چیف کمشنر انکوائری رپورٹ کا جائزہ لینے کے بعد کاروباری مرکز کو سیل کرنے یا نہ کرنے کے حوالے سے تحریری حکم جاری کرے گا۔ قواعد کے تحت ضرورت کے مطابق کاروباری مقام کا مکمل حصہ یا صرف مخصوص حصہ بھی سیل کیا جا سکے گا۔
ایف بی آر کے مطابق الیکٹرانک مانیٹرنگ کا بنیادی مقصد پیداوار، فروخت اور متعلقہ کاروباری سرگرمیوں کے ڈیٹا کو ریئل ٹائم بنیادوں پر ریکارڈ اور رپورٹ کرنا ہے تاکہ ٹیکس نظام میں دستاویز بندی اور شفافیت بہتر بنائی جا سکے۔ ایف بی آر پہلے ہی مختلف شعبوں میں ویڈیو اینالیٹکس اور الیکٹرانک مانیٹرنگ کے نظام متعارف کرا چکا ہے۔
ایف بی آر کی جانب سے مخصوص شعبوں میں الیکٹرانک مانیٹرنگ کیلئے عدم تعمیل کی صورت میں جرمانوں اور دیگر قانونی کارروائی کے ساتھ کاروباری مقامات سیل کرنے کی گنجائش بھی موجود ہے۔
دوسری جانب کاروباری اداروں کیلئے 10 فیصد ٹیکس کریڈٹ کا اقدام مانیٹرنگ اور انضمام کیلئے درکار ٹیکنالوجی پر ہونے والی سرمایہ کاری کی لاگت کو جزوی طور پر ٹیکس کریڈٹ کے ذریعے ایڈجسٹ کرنے کا طریقہ فراہم کرتا ہے۔ تاہم یہ سہولت صرف متعلقہ الیکٹرانک وسائل کی خریداری، تنصیب اور تنفیذ پر ہونے والی اہل سرمایہ کاری کیلئے ہے جبکہ آپریشن اور مینٹیننس کے اخراجات اس کریڈٹ میں شامل نہیں ہوں گے۔