Connells expects price growth to reach 2.5% in 2028 as easing inflation could allow borrowing costs to fall and encourage more buyers back into the market. Growth is then forecast to slow to 2% in 2029, when uncertainty ahead of the next general election may weigh on demand, particularly in London and southern England.
The group estimates that housing transactions in 2026 will fall around 100,000 short of the number expected at the start of the year. It forecasts activity to improve to about 1.1 million completed home moves in 2027 and just under 1.2 million in 2028, before easing to around 1.1 million in 2029. Lower mortgage rates are expected to help some households who postponed moving return to the market. However, Connells’ research director, Aneisha Beveridge, cautioned that if mortgage rates remain around 5%, house prices could fall slightly in 2027 instead of rising.
Households refinancing fixed-rate mortgages taken out before rates began increasing may also continue to face higher repayments, although that pressure is expected to begin easing by mid-2027. London house prices are forecast to fall by 1% in 2026 before rising 2% in 2027.
Outer London could benefit from improved mortgage affordability, but higher taxes and weaker investor and international demand may limit the capital’s recovery. Scotland and the Northeast of England are expected to remain among the stronger-performing areas, partly because their comparatively lower prices leave more room for buyers to respond to reduced borrowing costs.
Connells says wage growth has helped household affordability, while inflation has reduced house prices in real terms. Government measures have supported first-time buyers and the lower end of the market, but stamp duty and other tax costs continue to weigh on mainstream and higher-value properties.
Published: November 2, 2026 - 4:01 PM
Great Britain House Prices Forecast to Rise 1.5% in 2027
برطانیہ میں 2027 کے دوران گھروں کی قیمتوں میں 1.5 فیصد اضافے کی پیش گوئی
▫️ Connells Group expects prices to grow faster in 2028 as lower mortgage rates support demand
House prices across Great Britain are forecast to rise by 1.
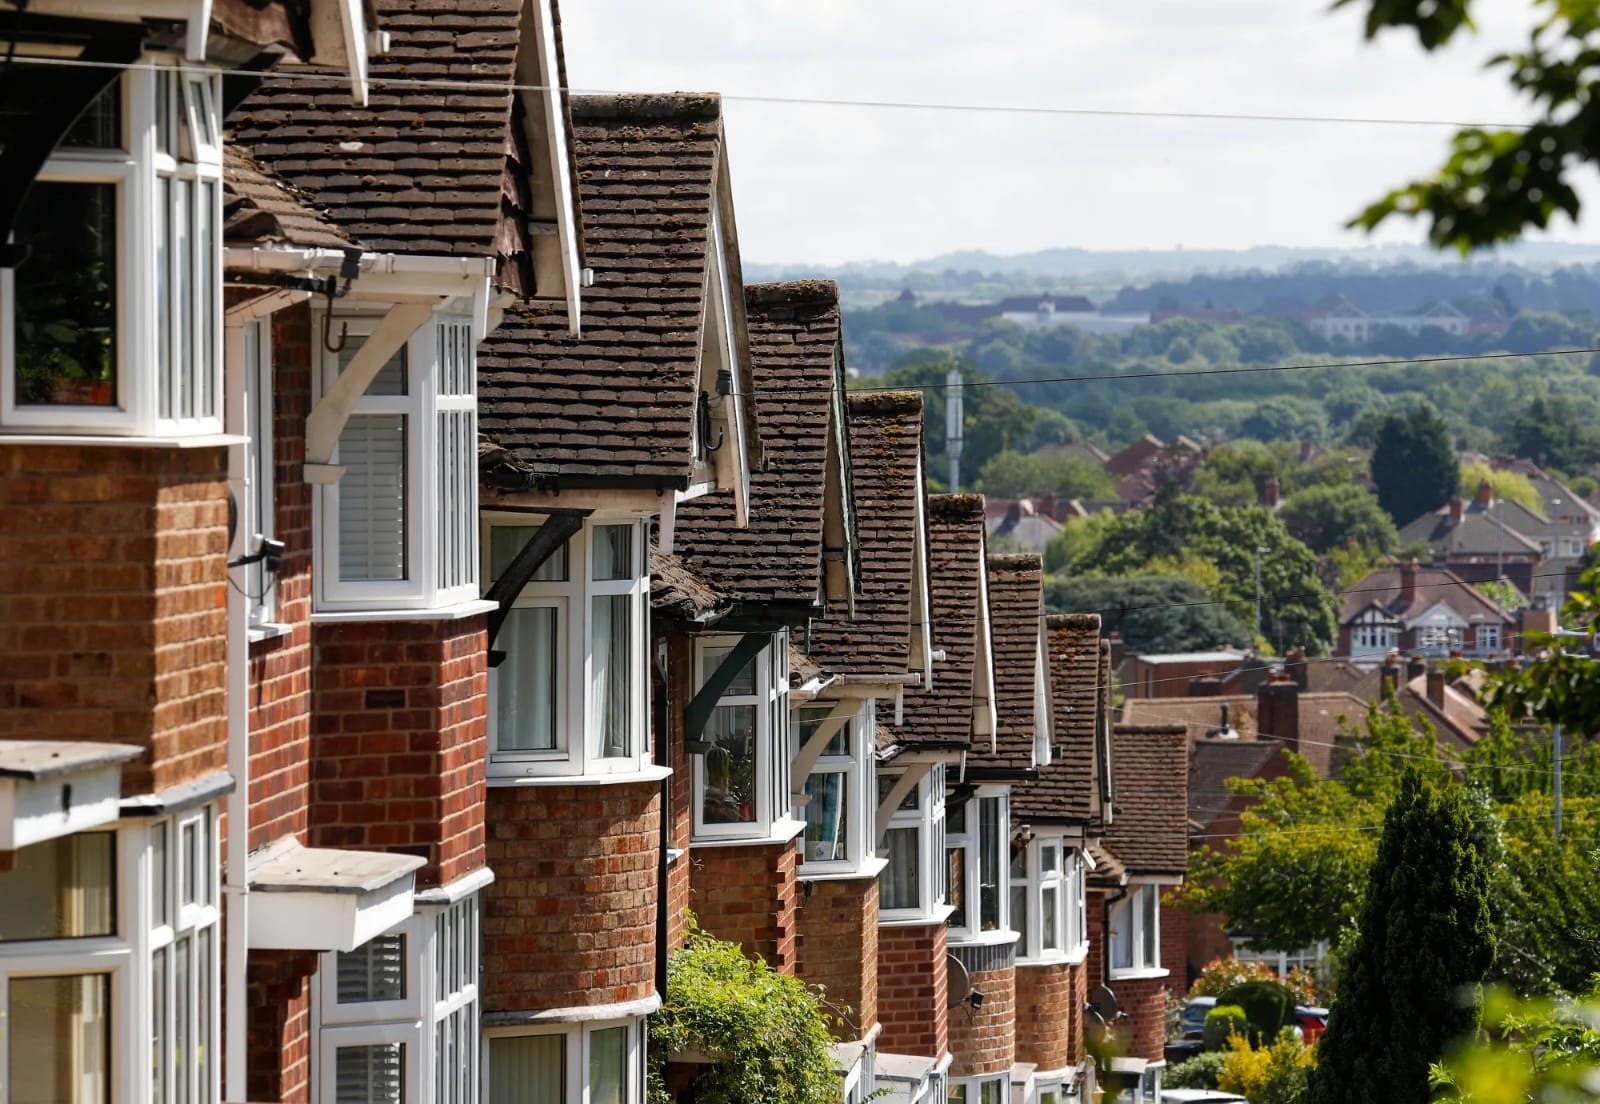
House prices across Great Britain are forecast to rise by 1.5% in 2027, following estimated growth of 1% in 2026, according to a new outlook from property agency Connells Group. The forecast covers England, Scotland and Wales; the article does not provide a separate forecast for Northern Ireland. London is assessed separately.